
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Six sectors remain in Leading: Consumer Staples (XLP), Financials (XLF), Materials (XLB), Communication Services (XLC), Health Care (XLV) and Energy (XLE).
- Materials becomes the strongest daily performer: XLB gained 1.69%, recording the largest advance among all eleven sectors.
- Communication Services strengthens: XLC rose 1.39%, supporting its Leading position.
- Financials and Health Care advance: XLF gained 0.80%, while XLV increased 0.75%.
- Utilities and Real Estate remain Improving: XLU and XLRE continue to show improving relative momentum.
- Technology enters Lagging: XLK moved into the Lagging quadrant after remaining in Weakening previously.
- Industrials and Consumer Discretionary lag: XLI and XLY remain in Lagging, indicating continued relative weakness.
- Broad market participation improves: Nine of eleven sectors advanced, with only Technology and Real Estate declining.
The latest US sector momentum visualization for 2 September 2026 shows a more constructive rotational structure, with six sectors positioned in Leading, two in Improving and three in Lagging, while no sectors remain in Weakening. Materials, Communication Services, Financials, Health Care, Consumer Staples and Energy occupy the Leading quadrant, while Utilities and Real Estate remain Improving. Technology has moved into Lagging alongside Industrials and Consumer Discretionary.
The improvement in short-term sector performance is also notable, with nine of eleven sectors recording gains. This represents a significant improvement in Market Breadth compared with the previous session.
Momentum Breakdown by Quadrant
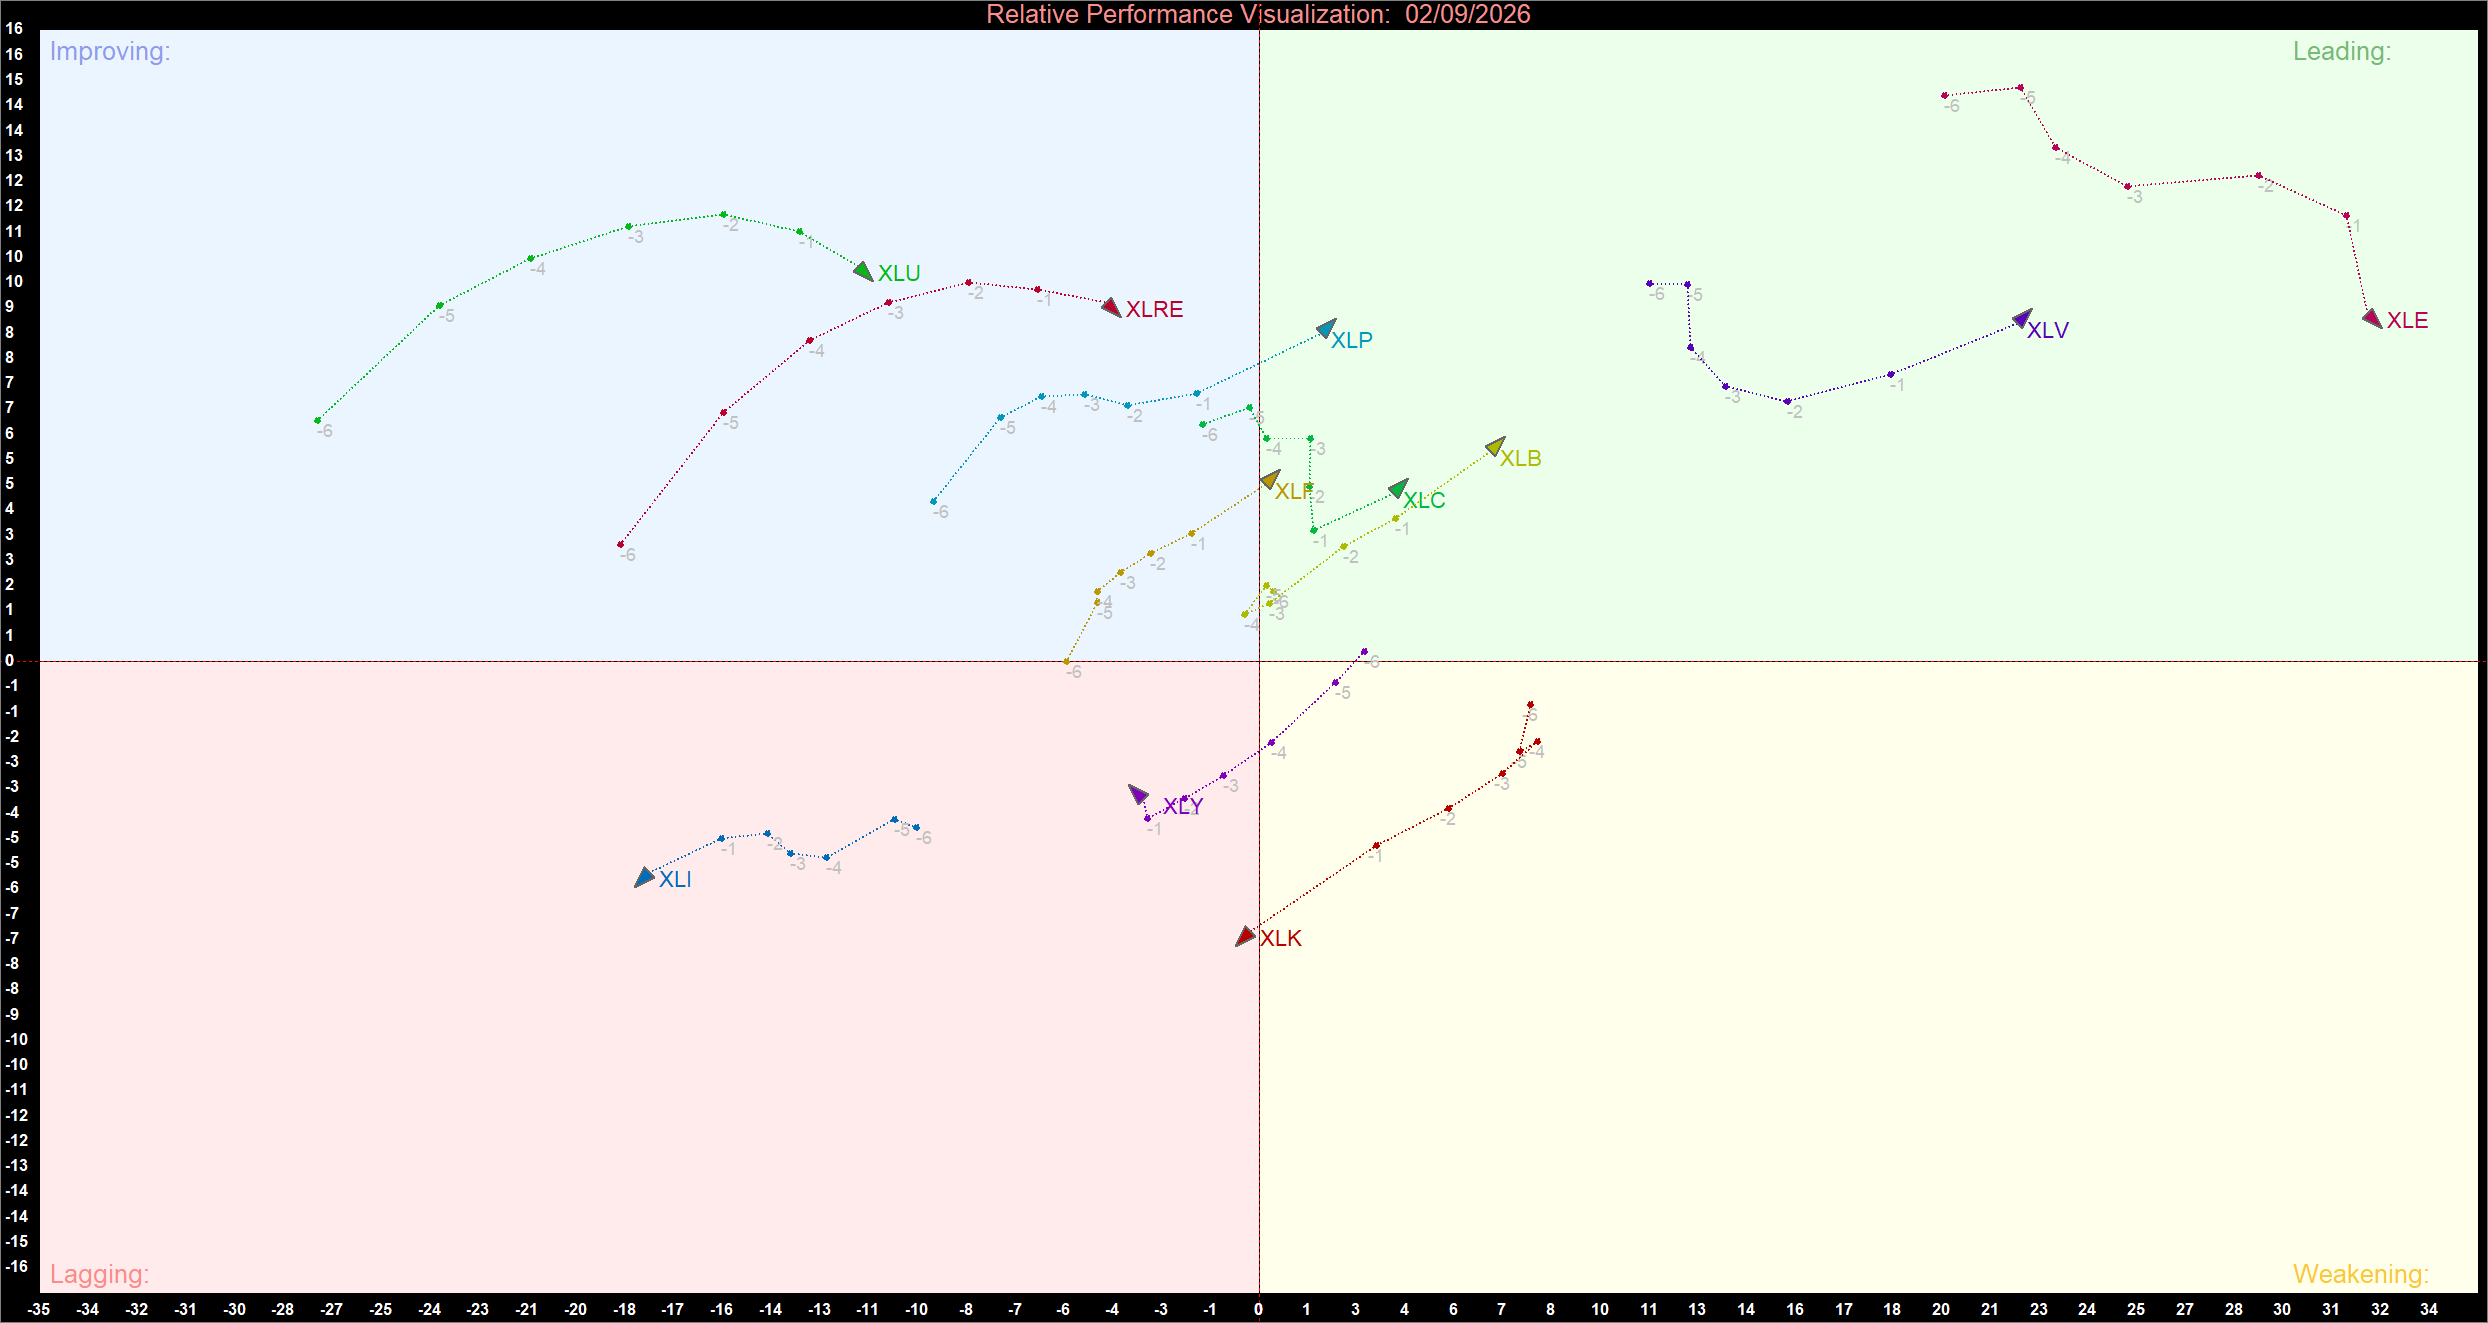
US Sector Relative Momentum Chart (at the closing price of 02/09/2026). Powered by AmiBroker.
Leading: Consumer Staples, Financials, Materials, Communication Services, Health Care and Energy
Consumer Staples (XLP), Financials (XLF), Materials (XLB), Communication Services (XLC), Health Care (XLV) and Energy (XLE) are positioned in the Leading quadrant.
Materials stands out as the strongest daily performer, gaining 1.69%. Communication Services followed with a 1.39% advance, while Financials and Health Care gained 0.80% and 0.75%, respectively. Energy also remained positive, rising 0.51%.
Consumer Staples gained 0.33%, reinforcing its Leading position despite its relatively modest daily return.
The expansion from four Leading sectors in the previous session to six indicates that relative Leadership has broadened. The continued direction of the RRG trajectories will be important in determining whether this broader leadership can be sustained.
Improving: Utilities and Real Estate
Utilities (XLU) and Real Estate (XLRE) remain in the Improving quadrant.
Utilities continues to display stronger relative momentum, while Real Estate is positioned closer to the centre of the RRG. Their positions indicate that relative momentum is improving, although neither sector has yet moved firmly into the Leading quadrant.
A continued move toward the upper-right of the RRG would increase the probability of these sectors transitioning into Leading. Stronger relative price performance would provide additional confirmation of this potential rotation.
Lagging: Technology, Industrials and Consumer Discretionary
Technology (XLK), Industrials (XLI) and Consumer Discretionary (XLY) are now positioned in the Lagging quadrant.
Technology's move into Lagging is particularly significant. XLK was previously positioned in Weakening, but its latest position indicates that its relative momentum has deteriorated further. The sector was also virtually unchanged on the day, declining just 0.02%, despite the broader market rally.
Industrials gained only 0.03%, while Consumer Discretionary advanced 0.24%. Despite these modest gains, both remain in Lagging, indicating that their broader relative performance continues to trail the market.
A sustained move toward the centre of the RRG would provide the first indication that these sectors are beginning to recover.
Strategic Summary
The latest US sector momentum analysis shows six sectors in Leading, two in Improving and three in Lagging, representing a broadening of market leadership.
Materials is the standout sector after gaining 1.69%, followed by Communication Services at 1.39%. Financials, Health Care, Energy and Consumer Staples also remain in Leading, while Utilities and Real Estate continue to improve.
Technology is the key development in the latest RRG, having moved from Weakening into Lagging. Industrials and Consumer Discretionary also remain in Lagging, keeping these three sectors among the weaker areas of the US Equity market.
Overall, the RRG indicates a broadly improving sector environment, supported by gains across nine of eleven sectors. The ability of Utilities and Real Estate to transition into Leading, together with any recovery in Technology, Industrials and Consumer Discretionary, will be important in determining whether the current improvement develops into a more sustainable broad-based market rotation.


 Nov 04, 2026





 Please wait processing your request...