
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
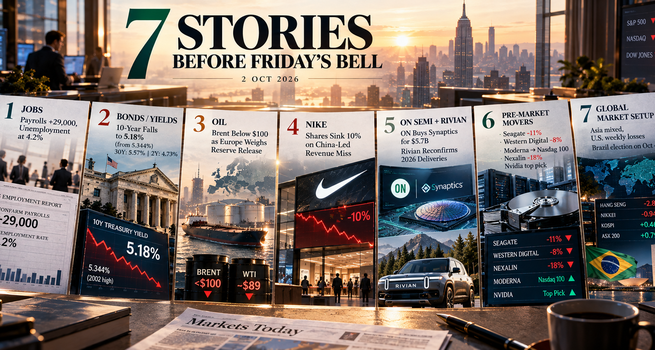
US stock futures rose after September payrolls came in well below forecasts, pushing the Unemployment rate to 4.2% and pulling Treasury yields off this week's 2002 highs as traders cut bets on an October Fed hike. Oil fell on reports Europe may release diesel and crude reserves, Nike shares sank 10% on a China-led Revenue miss, and ON Semiconductor agreed to buy Synaptics for $5.7 billion.
1. JOBS: Payrolls Rise Just 29,000 in September as Unemployment Climbs to 4.2% and Fed Hike Odds for October Collapse
US nonfarm payrolls increased by only 29,000 in September, well below the 84,000 to 90,000 consensus estimates, while the unemployment rate rose to 4.2% from 4.1%, both missing forecasts for a steady 4.1% reading. July and August payrolls were revised down by a combined 60,000, with August now showing a gain of 133,000 versus an initial 158,000 estimate and July revised to a loss of 10,000. Average hourly Earnings rose just 0.1% to $37.81, below the 0.3% forecast and the softest pace in months, while annual wage growth slowed to 3%, its weakest since May 2021. Health care, construction and Manufacturing added jobs while financial activities shed 7,000 positions, and the broader U-6 underemployment rate eased to 7.6% from 7.7%. Fed funds futures now price less than a 15% chance of an October rate hike, down sharply from earlier this week, with better than a 70% chance of a hike still priced for December. US stock futures jumped on the data, with S&P 500 futures up about 0.9%, Dow futures up more than 450 points and Nasdaq-100 futures up around 1%.
- A payrolls miss this wide, paired with 60,000 in downward revisions to the prior two months, shows the labor market cooling faster than the unemployment rate alone suggests, which is why futures rallied on bad news.
- Risk note: with October hike odds now below 15%, any upside surprise in next month's data could snap expectations back toward a hike almost as quickly as this week's selloff in bonds reversed.
2. BONDS/YIELDS: 10-Year Falls to 5.18% as the Jobs Miss Confirms Thursday's Retreat From a 2002 High of 5.34%
The 10-year Treasury Yield fell about 6 basis points to 5.18% on Friday, extending its pullback from Thursday's intraday peak of 5.344%, the highest level since April 2002, while the 30-year eased to 5.57% and the 2-year, the most sensitive to Fed policy, fell to 4.73%. European 10-year yields also declined roughly 3 basis points across major economies, easing pressure from this week's broader bond selloff that had been driven by concerns over elevated Inflation and hawkish Central Bank commentary. Gold rebounded above $4,200 an ounce on the weak jobs data, reinforcing expectations the Fed will hold rates steady this month, while falling oil prices added to the disinflationary backdrop supporting the bond market.
- Yields falling in the same session gold rises above $4,200 shows the jobs miss resetting the entire rate-path trade at once, from sovereign bonds to precious metals, rather than moving one Asset Class in isolation.
- Risk note: Thursday's spike to a 2002 high came from Deficit and inflation concerns that the jobs data has not resolved, so any rebound in that narrative could push yields back toward this week's peak even with the Fed now expected to hold.
3. OIL: Brent Falls Below $100 as Europe Weighs Releasing Diesel and Crude Reserves Under US Pressure
Brent crude fell more than 2.5% to below $100 a barrel and WTI dropped nearly 4% to about $89, extending losses after a report that European nations are considering releasing strategic diesel and crude reserves following pressure from the Trump administration to do so "immediately." Russian President Vladimir Putin said he will not sell diesel to the rest of the world until sanctions on Russia are lifted, after Moscow imposed its own export ban in response to Ukrainian strikes on its refineries, while Chinese refiners have separately suspended exports for October. The US reportedly told France and Germany to release their diesel reserves or face an export ban on American fuel stocks. Separately, the US is sending up to 10,000 additional troops to the Middle East, including a third aircraft carrier expected to arrive by the end of November, as Trump weighs resuming strikes on Iran after rejecting a ceasefire proposal and signaling attacks could restart after the November 3rd midterm elections.
- Oil dropping on a reserve-release report even as Russia hardens its own export stance shows the market pricing relief from European and American Supply action faster than it is pricing the risk of renewed Middle East conflict.
- Risk note: a strategic reserve release would be a one-time supply addition, so any confirmation that Trump resumes strikes on Iran after the midterms would reintroduce the geopolitical premium this week's price action has largely erased.
4. NIKE: Shares Sink 10% for a Second Straight Day as China Weakness Drives a Revenue Miss and a $2.5 Billion Cost-Cutting Plan
Nike (NYSE:NKE) shares fell 10.36% in premarket trading Friday, extending Thursday's decline, after the company reported fiscal first-quarter revenue down 4% to $11.2 billion on weakness in Greater China, partially offset by North America growth, with Net Income down 2% to $712 million. Chief Executive Elliott Hill said the company has "more work to do" in Nike Sportswear, Jordan Brand and Greater China, as Nike guided for high-single-digit revenue declines in fiscal 2027 and unveiled a new operating model called "Pace," targeting $2.5 billion in cost savings by 2031 alongside further staff layoffs beginning in 2027. The company has already cut jobs twice this year, including 775 roles at US distribution centers in January and 1,400 roles primarily in its tech division in April. Nike shares have fallen nearly 45% since the start of the year, and a Citi note said the firm remains neutral on the stock given sales guidance that came in below market expectations, adding there is "no justification" for Nike to trade at a premium multiple versus its growing peers.
- A 2nd straight day of double-digit-adjacent declines on top of a nearly 45% year-to-date drop shows the market treating Nike's China weakness as structural rather than cyclical, which is why a cost-cutting plan did not stabilize the stock.
- Risk note: Pace's savings target runs through 2031 with the layoffs only beginning in 2027, so near-term results will keep reflecting the China and Sportswear pressure the plan is meant to address years before it can show up in earnings.
5. M&A: ON Semiconductor to Acquire Synaptics for $5.7 Billion as Shares in Both Companies Jump
Synaptics (NASDAQ:SYNA) shares jumped more than 14% and ON Semiconductor (NASDAQ:ON) rose about 7% after the companies confirmed ON Semiconductor will acquire Synaptics for $123 per share in cash, a deal now valued at $5.7 billion, down from a prior agreement reported at $7 billion. Separately, Rivian (NASDAQ:RIVN) reconfirmed its 2026 delivery guidance of 65,000 to 70,000 vehicles after reporting third-quarter deliveries of 19,248 units, up 46% from 13,201 a year earlier and above Wall Street's estimate of 18,000, with growth driven by a ramp-up in production of its smaller, less expensive R2 SUV. To hit its full-year target, Rivian would need to lift fourth-quarter deliveries by at least 20.5% to 23,193 vehicles.
- Both companies in the ON Semiconductor-Synaptics deal rising together, rather than the usual pattern of an acquirer's shares falling on deal-financing concerns, shows investors reading the lower $5.7 billion valuation as a more disciplined price than the original $7 billion agreement.
- Risk note: Rivian's 46% delivery growth still requires a further acceleration of more than 20% next quarter to meet its own guidance, leaving execution risk concentrated entirely in the final 3 months of the year.
6. PRE-MARKET MOVERS: Seagate and Western Digital Fall Again on Toshiba's Capacity Expansion as Moderna Replaces Warner Bros Discovery in the Nasdaq 100
Seagate Technology (NASDAQ:STX) and Western Digital (NASDAQ:WDC) shares fell more than 11% and 8%, respectively, after Toshiba said it plans to double its hard disk drive production capacity for data centers and invest $380 million to expand facilities in the Philippines, its first major hard disk drive Investment in about 5 years. Moderna (NASDAQ:MRNA) will replace Warner Bros Discovery (NASDAQ:WBD) in the Nasdaq 100 effective October 9, with Moderna shares up 2.4% in premarket trading and up 563% over the past 12 months; Warner Bros Discovery is in the process of merging with Paramount (NASDAQ:PSKY), with that deal expected to close October 6. Separately, Vylor, a seeds and genetics company spun off from Corteva (NYSE:CTVA), was added to the S&P 500 in Corteva's place, with Corteva moving to the S&P MidCap 400. Nexalin Technology (NASDAQ:NXL) fell more than 18% despite announcing a 10-year distribution and manufacturing deal with Inovanexa Medical Technologies covering 7 South American countries. Morgan Stanley named Nvidia (NASDAQ:NVDA) its top semiconductor pick, citing Demand from a broad range of AI customers beyond the largest hyperscalers, with an overweight rating and $300 price target.
- Warner Bros Discovery's removal from the Nasdaq 100 landing just days before its deal with Paramount is set to close shows index membership mechanically following the corporate transaction rather than anticipating it.
- Risk note: Nexalin's 18% drop despite a new distribution agreement suggests investors are discounting the deal's near-term revenue contribution, so the stock's reaction to future updates on that rollout will be a test of how much Credit the market is willing to extend.
7. MARKET SETUP: Asia Closes Mixed as Hang Seng Falls 2.8% and Brazil Heads Into a High-Stakes Election Weekend
Asian markets closed mixed Friday, with Japan's Nikkei 225 down 0.94% to 68,309.46 and the Topix off 0.99%, while Hong Kong's Hang Seng fell 2.8% in its final hour of trade; South Korea's Kospi rose 0.46% and Australia's ASX 200 added 0.79%, while mainland China's markets were closed for a holiday. All 3 major US indexes remain on pace for weekly losses despite Friday's gains, with the Dow off 1.7% to 1.8% for the week, the S&P 500 down about 1.2% and the Nasdaq off roughly 0.8%, which would mark the S&P 500's worst weekly performance since August. Brazilians vote October 4th in the first round of a presidential election dominated by incumbent Luiz Inacio Lula da Silva and Senator Flavio Bolsonaro, a contest that could shape Brazil's trade and critical-minerals relationships with the US and China.
- All 3 major US indexes heading for a weekly loss even after Friday's jobs-driven rally shows this week's yield spike did lasting technical damage that a single data-driven bounce has not fully reversed.
- Risk note: Brazil's election outcome could shift critical-minerals access just as AI-driven demand for those materials is rising, so a result favoring either candidate's stated alignment could move related equities early next week.

 Oct 28, 2026
 Please wait processing your request...