
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
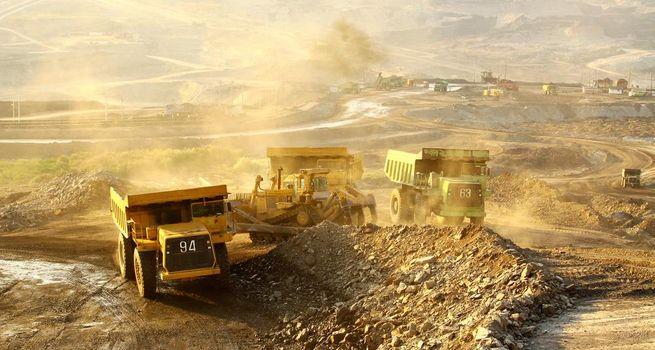
• Caledonia Mining centers its operations on the Blanket Mine in Zimbabwe, a long-established underground gold operation.
• The company is among the relatively few small-cap gold producers to maintain a consistent dividend policy.
• Concentrated exposure to Zimbabwe gives CMCL both a clear operational identity and a distinct country-risk profile.
• Investment in deepening and expanding the Blanket Mine has been central to Caledonia's production growth strategy.
In a gold-mining sector dominated by sprawling multinationals and speculative explorers, Caledonia Mining Corporation Plc (NYSEAMERICAN:CMCL) carves out an unusual niche: a focused, dividend-paying producer built around a single flagship mine. That combination of income and commodity leverage has periodically brought the stock back onto investors' radar, particularly during stretches when gold sentiment strengthens and yield becomes harder to find elsewhere. Caledonia's story is closely intertwined with Zimbabwe, where its Blanket Mine has produced gold for decades and where the company has concentrated its growth ambitions. For investors, the appeal lies in the rare pairing of a regular dividend with exposure to a precious metal, while the central tension revolves around the concentration of operations in one country.
Company Overview
Caledonia Mining is a gold producer whose operational heart is the Blanket Mine, a long-life underground gold operation located in Zimbabwe. The mine has a lengthy production history and has served as the company's primary cash generator and strategic anchor. Around this core asset, Caledonia has pursued additional interests within Zimbabwe, including exploration ground and development opportunities intended to broaden its production base beyond a single operation. The company is dual-listed and has historically courted international investors, positioning itself as a way to access Zimbabwean gold production within a corporate structure familiar to Western markets. Caledonia's identity differs from many peers in two respects: its tight geographic focus and its commitment to a dividend, which signals a degree of cash-flow stability unusual for a producer of its size.
For investors, CMCL represents focused exposure to gold mining executed through a long-running asset, with the company seeking to layer additional projects on top of that foundation.
Why the Stock Is in Focus
Caledonia Mining returns to investors' attention for several interlocking reasons. The most prominent is its dividend, which sets it apart in a category of small-cap gold miners that typically reinvest all available cash. When investors hunt for income alongside commodity exposure, a dividend-paying producer naturally surfaces in screens and discussions. A second driver is the broader gold environment; as bullion sentiment improves, the leverage embedded in producers' margins makes names like Caledonia more compelling. A third factor is the company's growth trajectory, including the investments it has made to deepen and expand its flagship mine, which can lift production and cash flow. Finally, the very feature that defines Caledonia, its concentration in Zimbabwe, generates ongoing debate. Country-specific developments, from currency policy to fiscal arrangements, can move the narrative meaningfully.
The interplay of income, gold leverage and single-country exposure keeps CMCL a recurring subject among precious-metals investors.
Gold, Silver and Precious-Metals Market Backdrop
The fortunes of any gold producer are inseparable from the precious-metals macro backdrop. Gold prices respond to real interest rates, inflation expectations, currency dynamics, central-bank buying and shifts in investor risk appetite. When uncertainty rises or real yields fall, bullion typically attracts safe-haven flows that lift the economics of producers across the sector. Silver and other precious metals often move alongside gold, though their industrial-demand components introduce additional variables. For a focused producer like Caledonia, the gold price is the dominant external driver, because revenue is tied almost entirely to ounces sold at prevailing rates. A stronger gold environment can expand margins meaningfully, given that a portion of mining costs is relatively fixed in the short run, while weaker prices compress profitability and can pressure dividend sustainability.
Understanding CMCL therefore requires attention to the same macro forces that shape the whole sector, since these set the broad limits on what the company can earn.
Key Catalysts Driving Investor Interest
Several catalysts shape the investment case for Caledonia Mining. Production and cost updates from the Blanket Mine are foremost, since the asset's performance directly determines cash generation and the capacity to sustain the dividend. Progress on capital projects, such as shaft deepening and expansion work designed to access deeper ore and lift throughput, offers a growth catalyst tied to higher future output. Exploration results, both at the flagship mine and across the company's broader Zimbabwean ground, can extend mine life or introduce new projects that reshape the production profile. Capital-allocation decisions, particularly the trajectory of the dividend, carry weight for the income-focused holders who are drawn to the stock. On the macro side, decisive movements in the gold price act as catalysts in their own right given producer leverage.
Country-level developments in Zimbabwe, including policy and currency matters, can also serve as swing factors that reframe sentiment toward the company.
Financial and Valuation Considerations
Financially, Caledonia is assessed through the lens common to gold producers rather than standard industrial yardsticks. Investors typically focus on all-in sustaining costs as a measure of operating efficiency, cash flow relative to capital spending, and the balance sheet's resilience during periods of heavy investment in the flagship mine. Because gold miners are price-takers, margin depends on the gap between realized gold prices and unit costs, making cost control a defining factor. The dividend introduces a yield dimension that some investors weigh prominently, and its sustainability is often analyzed in the context of cash flow and reinvestment needs. Valuation approaches include price-to-cash-flow comparisons against peers and net-asset-value estimates that discount future production. Any specific numbers should be treated as cyclical and variable, since mining results swing with both commodity prices and operational factors.
For CMCL, the interplay between a single-asset cost base, the gold price and the company's commitment to returning cash defines the core of its financial story.
Growth Outlook and Project Pipeline
Caledonia's growth outlook rests primarily on extending and optimizing the Blanket Mine while building out additional opportunities in Zimbabwe. The company has historically invested in shaft deepening and infrastructure to access deeper portions of the orebody, an effort designed to support steadier or higher production over a longer horizon. Beyond the flagship asset, Caledonia has pursued exploration ground and development prospects intended to diversify its production beyond a single mine, which would reduce reliance on Blanket over time. Successfully advancing a new project from exploration toward production would be a significant milestone, both for the additional ounces it could bring and for what it would signal about the company's ability to grow beyond its anchor asset. As with all miners, reserve replacement is a structural necessity, since production continually depletes resources.
The credibility of Caledonia's pipeline, and its capacity to fund growth while maintaining the dividend, sits at the center of the CMCL growth thesis.
Major Risks Investors Should Watch
The risks confronting Caledonia Mining blend sector-wide and company-specific elements. Commodity-price risk is paramount: a sustained gold decline would pressure margins and could threaten dividend sustainability. Country concentration is the most distinctive risk, as the company's heavy reliance on Zimbabwe exposes it to local currency policy, fiscal terms, power supply reliability and broader political and economic conditions. Operational risk attaches to running a deep underground mine, where ground conditions, equipment availability and grade variability all affect output. Single-asset dependence amplifies the consequences of any disruption at the flagship operation. Cost inflation in energy, labor or consumables can erode margins even when gold prices hold. Project-execution risk applies to expansion and development work, where delays and budget overruns are common across the industry. Currency translation and repatriation considerations can affect reported results and the flow of cash to shareholders.
Investors weighing CMCL typically balance its dividend appeal against this concentrated risk profile.
What Could Drive the Stock Next
The next phase for Caledonia Mining is likely to be shaped by the intersection of the gold price, operational delivery at the Blanket Mine and developments in Zimbabwe. A supportive bullion environment would bolster cash flow and reinforce the dividend, while weakness would test the company's cost discipline and capital-return capacity. The market will watch whether expansion and deepening investments translate into steadier or growing production, and whether exploration introduces meaningful new ounces or projects that diversify the asset base. Capital-allocation signals, especially the dividend's trajectory, will influence how income-focused investors view the stock. Country-level developments in Zimbabwe, from monetary policy to gold-sale and currency arrangements, can move sentiment independent of operations. Broader fund flows into and out of the gold-equity space will also play a role.
In sum, the path forward for CMCL depends on a blend of macro support, operational execution and effective management of its concentrated jurisdictional exposure.
Conclusion
Caledonia Mining occupies a particular and memorable place in the gold-mining landscape: a focused producer that pairs commodity exposure with a dividend, built around a long-life flagship mine in Zimbabwe. That blend of income and leverage explains why the stock periodically returns to investors' radar, especially when gold momentum builds and yield grows scarce. Yet the same concentration that gives Caledonia its clear identity also defines its principal risk, tying its fortunes closely to a single asset and a single country. As the gold cycle turns, Caledonia's ability to sustain its flagship operation, advance its pipeline and protect its dividend will shape whether the stock can hold investor interest. For those tracking dividend-paying exposure to gold, CMCL remains a compelling and instructive case study in focus, income and concentrated risk.

 Nov 04, 2026
 Please wait processing your request...