
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
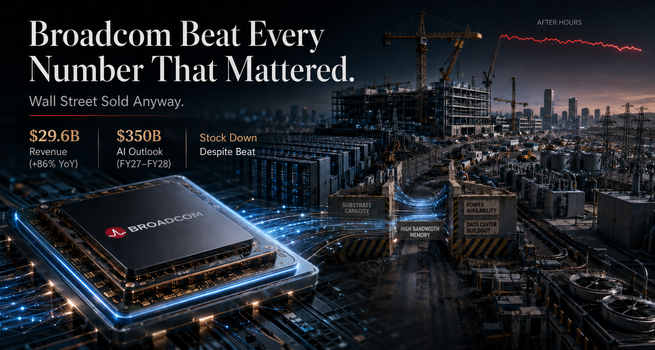
- Broadcom's fiscal third-quarter Revenue climbed 86 percent year-over-year to $29.6 billion, powered by AI semiconductor Demand that more than tripled from the prior year.
- Shares fell more than 2 percent after-hours and extended the decline into pre-market trading, even after a clean beat on revenue, profit, and cash flow.
- Management extended its AI chip revenue outlook through fiscal 2028, pointing to roughly $115 billion next year and $230 billion the year after, a combined $350 billion two-year figure.
- Operating margin hit a record even as gross margin compressed, a split company executives say reflects Operating Leverage rather than weakening profitability.
- A third-party financing platform is now Underwriting a slice of the AI buildout for Broadcom's largest customers, keeping the heaviest exposure off its own balance sheet.
The Reaction That Didn't Match the Results
Broadcom's (NASDAQ:AVGO) fiscal third quarter was, by nearly every conventional measure, one of the strongest in the company's history. Revenue rose 86 percent year-over-year to $29.6 billion. Operating Income climbed 92 percent. Free Cash Flow hit a record $13.7 billion. AI semiconductor revenue alone more than tripled. Every one of those figures cleared the bar analysts had set going into the print.
The stock fell anyway. Shares dropped more than 2 percent in after-hours trading immediately following the release, then extended that slide into the next morning's pre-market session, at one point trading down nearly 3 percent from the prior close.
The gap between the results and the reaction is not really about this quarter at all. It's about one number buried inside an otherwise dominant report: fourth-quarter revenue guidance of approximately $34.8 billion, which landed just below what some Sell-Side models had built in. In a sector where valuations are set by the steepness of the forward curve rather than the size of the trailing quarter, a guidance figure that merely meets expectations instead of exceeding them gets read as a warning sign, however unearned. What actually happened underneath that single data point tells a much more constructive story, and it's one that stretches out two full fiscal years.
A Two-Year Number That Changes the Frame
The headline from Broadcom's Earnings Call wasn't the quarter just completed. It was the guidance that came with it. Management extended its AI semiconductor revenue outlook through fiscal 2028, and the scale of it reframes how the stock should be read from here.
Fiscal 2027 AI chip revenue is now projected at approximately $115 billion, up from a prior forecast of just over $100 billion. Fiscal 2028 is expected to roughly double again, to $230 billion. Together, that's close to $350 billion in cumulative AI semiconductor shipments across the two years, a figure large enough to function as its own Investment thesis independent of any single quarter's guidance miss.
Crucially, executives described this as secured supply, not aspirational demand. Actual customer appetite, they said, already exceeds the numbers being guided to. The constraint sits on Broadcom's side of the table, tied to how much it can manufacture and ship, not on any softness from buyers. That distinction matters in a market that has spent much of the year second-guessing whether AI Capital spending can keep compounding at its current pace. Here, the limiting Factor isn't demand. It's execution.
That demand is also highly concentrated. Broadcom works with a small number of large customers building custom AI accelerators, known internally as XPUs, and management indicated that two of the largest are on track to become its biggest AI chip customers by 2027 and 2028, each with visibility into double-digit gigawatts of planned deployment. A third major customer is scaling its own custom accelerator program, with additional generations already in development. Alongside the chips, Broadcom's AI networking business, the switches and interconnects that link thousands of accelerators into a single working system, is growing at a comparable pace, giving the company a foothold on both sides of the AI Data Center build-out.
One distinction from the call is worth holding onto: gigawatts of planned capacity and dollars of recognized revenue are not the same thing. Not every gigawatt a customer commits to gets deployed within a given fiscal year, since building the surrounding data center, securing power, and finishing construction all take time. The revenue guidance, executives said, is a deliberately conservative translation of a much larger addressable gigawatt figure into what the company believes it can realistically ship and recognize within that window.
Why Margins Are Splitting in Two Directions
Look closely at the P&L and there's a genuine tension worth understanding, not explaining away. Gross margin narrowed during the quarter, and it will likely keep narrowing as AI chips take up more of Broadcom's revenue mix. Custom AI accelerators carry significantly more memory content than the company's legacy semiconductor products, and that memory dilutes gross margin even as it drives the topline higher. This is structural, not a sign of pricing pressure.
Operating margin moved the opposite way, climbing to a record. Management's case, repeated more than once on the call, is that gross margin is simply the wrong metric to anchor on here. Revenue growth in the semiconductor segment is outpacing Operating Expense growth by such a wide margin that the company is capturing substantial operating leverage even as its product mix shifts toward lower-gross-margin, higher-volume AI silicon. Fourth-quarter guidance calls for Operating Margin of roughly 66 percent, essentially flat year-over-year, despite a further step down in gross margin.
Infrastructure software is doing quieter, complementary work in the background. Revenue and annual Recurring Revenue both grew, and software operating margin expanded year-over-year, giving the company a high-margin counterweight to the memory-driven pressure building in semiconductors. Management also pointed to rising enterprise interest in running AI workloads on private infrastructure through its virtualization platform, a smaller but potentially durable growth lever as large enterprises look to repatriate workloads from public cloud.
Who's Actually Financing This Build-Out
The most structurally interesting part of the quarter had nothing to do with chips directly. Broadcom is now routing a portion of its AI infrastructure exposure through a financing platform built with outside capital partners, designed to help fund large-scale compute deployments for select customers whose cash flow hasn't yet caught up to their infrastructure ambitions.
The logic is straightforward. Two of Broadcom's largest AI customers are still in a phase where the capital required to build out compute capacity outpaces current operating cash flow. Rather than financing that gap directly on its own balance sheet, Broadcom is partnering with third-party investors who independently underwrite and Capitalize the assets. Its own exposure is limited to modest residual value guarantees, which management characterized as low-risk contingent liabilities given the profitability trajectory of the customers involved and the durability of the underlying hardware. Future arrangements, executives said, will be evaluated deal by deal, with terms tailored to each customer and investor group rather than following a single template.
It's a structure worth watching well beyond Broadcom itself. It signals how the entire AI infrastructure ecosystem is financing itself at this stage of the cycle, increasingly through purpose-built vehicles that spread risk across specialized capital providers, rather than sitting entirely on the balance sheets of either the chipmakers or the AI labs.
The Real Constraint Isn't Demand
Ask Broadcom's executives what could actually derail this outlook, and the answer isn't customer appetite. It's everything Downstream of it: substrate capacity, high-bandwidth memory supply, and the unglamorous physical work of building data centers, securing power, and getting sites construction-ready. Broadcom is expanding its own substrate Manufacturing capacity, along with laser and optical component capacity used in AI networking gear, and next year's Capital Expenditure guidance reflects that build-out directly.
There's also a useful detail on pricing dynamics across chip generations. As each new generation of AI accelerator becomes more powerful, it also draws more power per chip, meaning fewer chips are needed to Fill out a gigawatt of capacity. The net effect, according to management, is that Broadcom's dollar content per gigawatt should stay relatively stable across generations even as individual chip prices rise. The growth story here is less about pricing power on any single chip and more about how quickly the physical infrastructure supporting these deployments can actually get built.
That's the frame worth carrying forward. Broadcom's AI chip Business is no longer demand-constrained. It is execution-constrained, across silicon, memory, and concrete. How fast that execution moves will likely matter more to the stock over the next two years than any single quarter's guidance number.


 Nov 17, 2026





 Please wait processing your request...