
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed higher on Tuesday after softer headline and core inflation reduced expectations of a Federal Reserve rate hike this month. The S&P 500 rose 0.4%, the Nasdaq gained 1.1%, and the Dow edged higher, supported by a rebound in semiconductor stocks and strong bank earnings. Nvidia, Broadcom and Micron advanced, while JPMorgan, Bank of America and Goldman Sachs gained following upbeat results. In contrast, Citi declined after earnings, and IBM plunged 25.2% after missing expectations and warning of weaker client spending.
Market Movers
Among the top-performing stocks of the session NextCure, Inc. surged 201.83%, while Twin Vee PowerCats Co. rallied 54.91%. On the losing side, Leslie's, Inc. fell 41.07%, while STAK Inc. declined 40.13%, making them the weakest performers during the trading day.
Commodities Update
WTI crude rose above USD 79 per barrel and Brent climbed past USD 85 on Wednesday, reaching one-month highs after three consecutive sessions of gains, as escalating US-Iran tensions heightened concerns over supply disruptions near the Strait of Hormuz. Prices were supported by renewed US strikes on Iranian military assets, the reinstatement of a naval blockade around Iranian ports and President Trump’s pledge to intensify operations until Iran stops attacking vessels and reopens the waterway. Trump also dropped a proposed 20% fee on cargo transiting Hormuz, citing expectations of stronger future investment from Gulf nations in the US.
Gold eased toward USD 4,000 per ounce and silver slipped toward USD 58 on Wednesday, giving back part of the previous session’s gains as renewed US strikes on Iran and the reinstatement of a naval blockade near the Strait of Hormuz heightened concerns over energy-driven inflation and interest rates. Both metals had risen after softer-than-expected US inflation data reduced expectations for an imminent Federal Reserve hike, while Fed Chair Kevin Warsh reaffirmed the central bank’s commitment to price stability without adopting a more hawkish stance. Markets nevertheless continued to assign roughly a 50% probability to a September rate increase.
Macro Updates
Higher Mortgage Rates Weigh on US Housing Demand
US mortgage applications fell 2.7% in the week ended July 10, marking a second consecutive weekly decline, as the average 30-year fixed mortgage rate increased to 6.65%, near its highest level in several months. Rising Treasury yields, driven by inflation concerns and expectations of possible Federal Reserve rate increases, pushed borrowing costs higher and weakened housing demand. Purchase applications declined by more than 7%, indicating softer homebuying activity, while the refinancing figures provided showed mixed movements.
US Producer Inflation Expected to Moderate in June
US producer prices are forecast to remain unchanged in June 2026, the weakest monthly reading in ten months, as lower energy costs offset broader price pressures. Headline annual inflation is expected to ease to 6.2% from 6.5%, marking its first slowdown in eight months. However, core producer prices are projected to rise 0.4% month over month, while annual core inflation could accelerate to 5.2%, its highest level since December 2022, indicating persistent underlying inflationary pressure.
US Dollar Weakens as Softer Inflation Eases Rate-Hike Expectations
The US dollar index fell below 101 on Wednesday, extending losses for a second session after weaker-than-expected June inflation reduced expectations of an imminent Federal Reserve rate increase. Annual inflation slowed to 3.5%, while consumer prices declined 0.4% month over month, marking the first monthly fall since 2020. However, renewed US-Iran tensions and rising oil prices kept inflation risks elevated, with markets still pricing in roughly a 50% probability of a September rate hike.
US Crude Stocks Decline Modestly as Production Reaches a New High
US crude oil inventories fell by 564,000 barrels in the week ended July 10, below expectations for a 2.7 million-barrel draw, while Cushing stocks increased by 238,000 barrels. Gasoline inventories declined by 1.66 million barrels, whereas distillate stocks rose by 2.3 million barrels. The Strategic Petroleum Reserve dropped to 316.5 million barrels, its lowest level in more than 43 years, while domestic oil production increased to 13.86 million barrels per day.
Bonds Commentary
The US 10-year Treasury yield held near 4.59% on Wednesday after softer-than-expected June inflation data reduced concerns over an immediate Federal Reserve rate hike. Annual inflation slowed to 3.5%, while consumer prices fell 0.4% month over month, the first decline since 2020. However, renewed US-Iran tensions and higher oil prices kept inflation risks elevated, leaving markets to price in roughly a 50% chance of a September rate increase.
Futures Update
US equity futures were little changed on Wednesday as investors awaited June producer-price data for further clues on the Federal Reserve’s policy outlook. Expectations for firmer core producer inflation contrasted with the previous session’s softer CPI report, while renewed US-Iran tensions pushed energy prices and Treasury yields higher. Even so, strong corporate earnings supported sentiment, with ASML’s upbeat signals lifting AMD and Intel, while Morgan Stanley gained after joining other major US banks in reporting solid results. 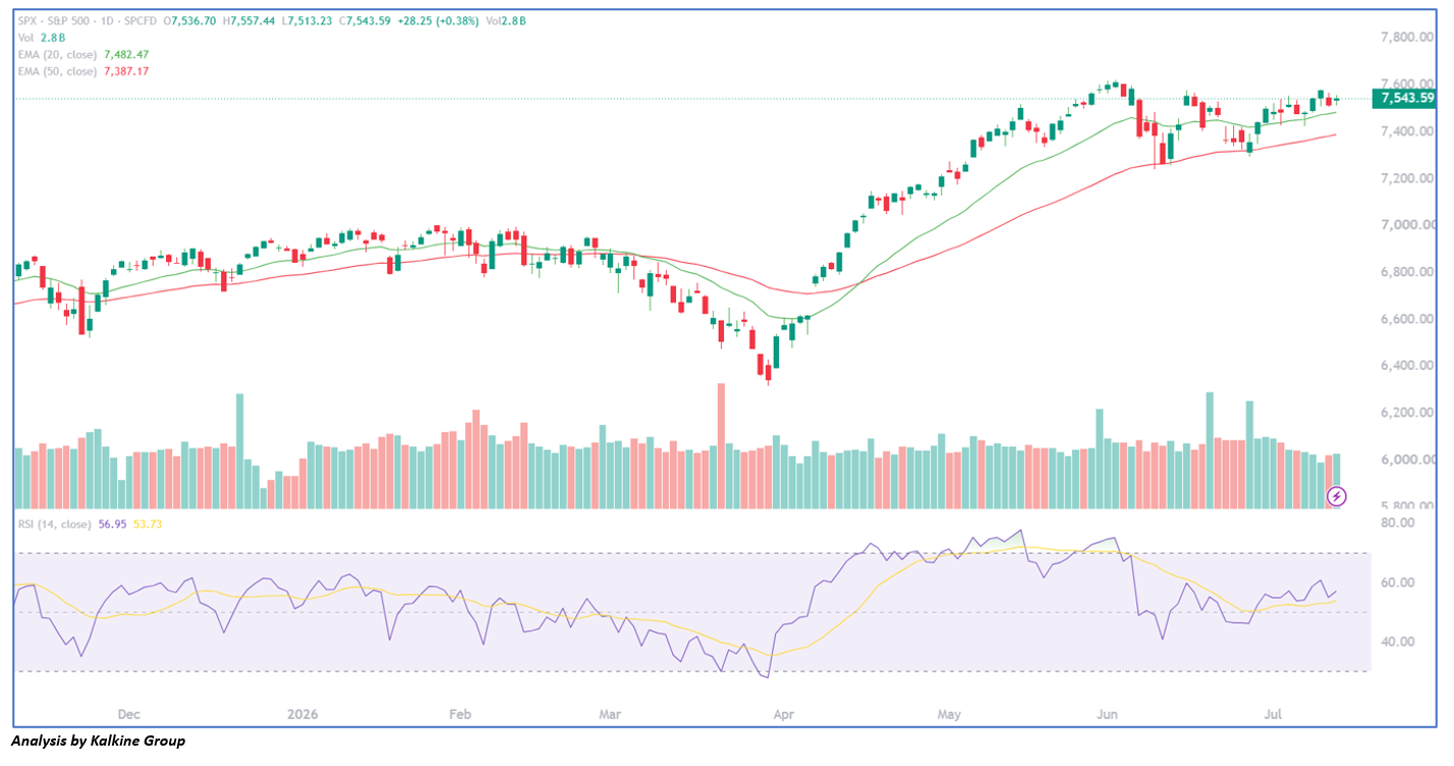
After the weakness seen in the previous session, U.S. stocks rebounded on Tuesday, with the major indices ending higher and the tech-heavy Nasdaq leading the gains. The S&P 500 maintained a constructive intraday outlook, continuing to trade well above its 20-day and 50-day EMAs, highlighting the strength of the prevailing uptrend. The index is consolidating just below its recent highs, indicating that buyers remain in control despite subdued momentum. Meanwhile, the RSI is hovering around 57, reflecting healthy bullish momentum without signaling overbought conditions. A decisive breakout above the recent resistance could pave the way for further gains, while the 20-day EMA is likely to serve as the first line of support on any near-term pullback.

 Nov 13, 2026
 Please wait processing your request...