
 CA
 NZ
 UK
 AU
 IND

 US
Lexicon Pharmaceuticals, Inc
Lexicon Pharmaceuticals, Inc (NASDAQ: LXRX) is a biopharmaceutical firm dedicated to developing the drug candidates pilavapadin, LX9851, and sotagliflozin, while also marketing its approved product INPEFA. The company is advancing pilavapadin (LX9211), an orally administered small-molecule therapy, for potential use in treating neuropathic pain.
Key Growth Aspects
Key Risks
Technical Observation (on the daily chart):
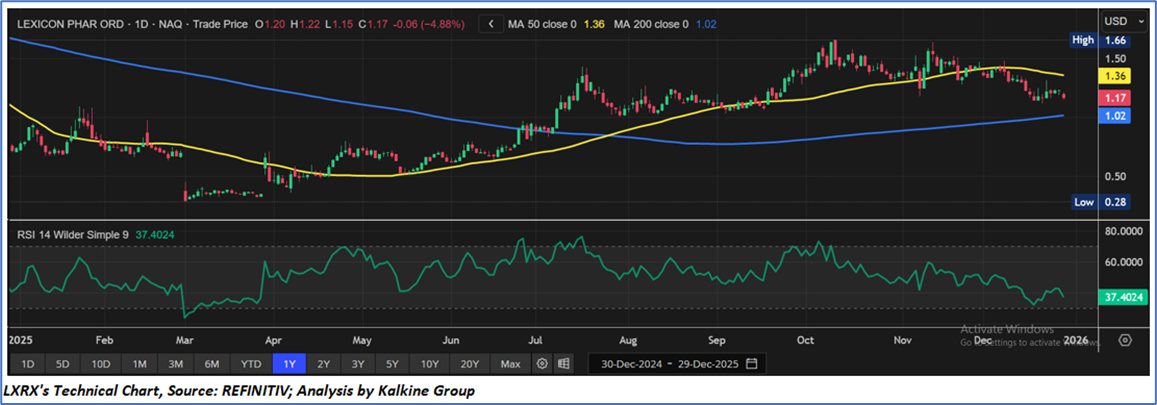
Lexicon Pharmaceuticals’ chart shows the stock in a short-term correction within a still-intact longer-term uptrend. After peaking near USD ~1.65, the price has slipped below the 50-day moving average while remaining above the 200-day, indicating weakening momentum but not a full trend breakdown. The RSI near 37 reflects bearish short-term sentiment without being deeply oversold.
Lexicon Pharmaceuticals delivered a strong third quarter of 2025, underscored by meaningful R&D progress, expanding strategic partnerships and a significantly improved financial profile. Key milestones included advancing pilavapadin toward Phase 3 readiness in diabetic peripheral neuropathic pain, completing IND-enabling studies for LX9851 with Novo Nordisk now preparing for clinical development, and accelerating global enrollment in the pivotal SONATA-HCM Phase 3 trial of sotagliflozin. Financially, revenues grew sharply to USD 14.2 million, supported by licensing income and ongoing INPEFA® sales, while disciplined cost management reduced operating expenses and cut net losses materially. With a solid cash position and multiple high-value catalysts expected in 2026, the company appears well positioned to unlock sustained long-term value.
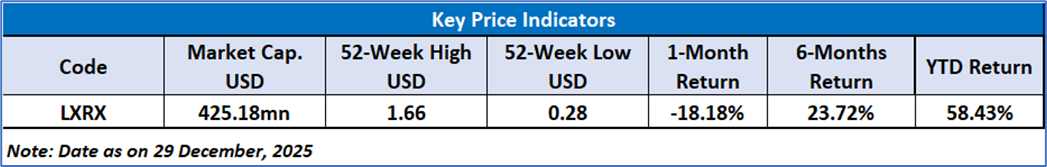
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Buy’ rating has been given Lexicon Pharmaceuticals, Inc (NASDAQ: LXRX) at the closing market price of USD 1.17 as of Dec 29,2025.
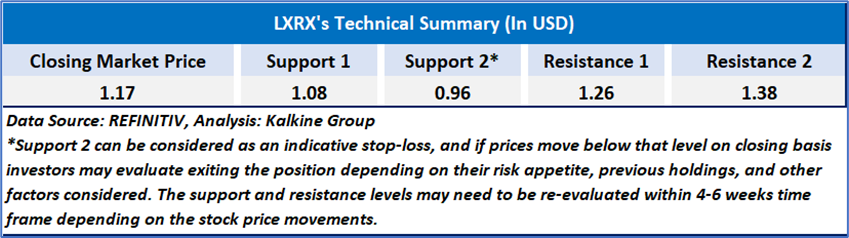
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is December 29,2025. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.
Kalkine Equities LLC, with Delaware File Number 4697384, Foreign Qualification Registration in California File Number 202109211078, and Texas File Number 805521396, is authorized to provide general advice only. The information on https://kalkine.com/ does not take into account any of your investment objectives, financial situation or needs. You should consider the appropriateness of advice taking into account your own objectives, financial situation and needs and seek independent financial advice before making any financial decisions. The link to our Terms and Conditions and Privacy Policy has been provided for your reference. On the date of publishing the reports (mentioned on the website), employees and/or associates of Kalkine do not hold positions in any of the stocks covered on the website. These stocks can change any time and readers of the reports should not consider these stocks as advice or recommendations later.
Past performance is not a reliable indicator of future performance.
 Please wait processing your request...