
 CA
 NZ
 UK
 AU
 IND

 US
Target Corporation
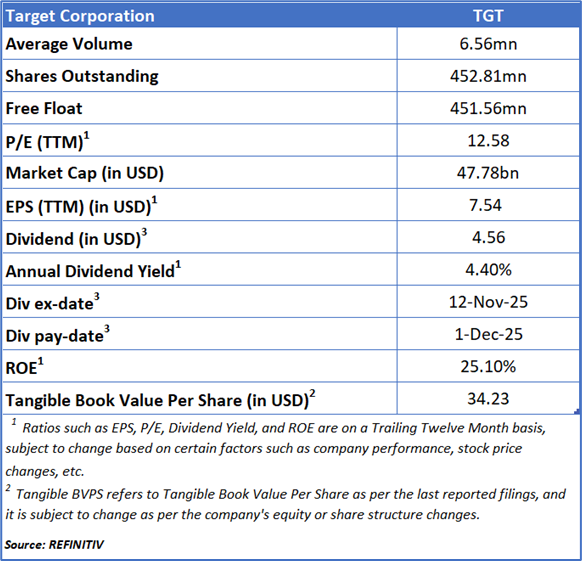
Target Corporation (NYSE: TGT) operates as a general merchandise retailer, serving customers through an integrated network of physical stores and digital channels. The company offers a broad assortment of everyday essentials alongside differentiated, design-led merchandise, positioned at accessible and value-oriented price points.
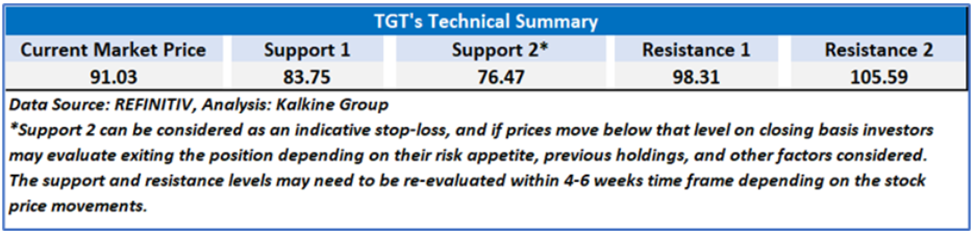
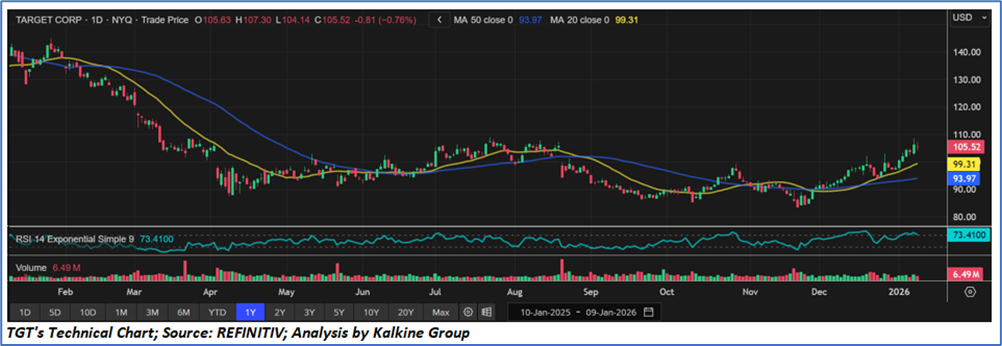
As per US Inflation Report published on ‘TGT’ on Nov 28, 2025, Kalkine provided an ‘Buy’ stance on the stock at USD 91.03 based on fundamental analysis and the stock price has now moved up by ~ 15.92% since then.
Noted below are the details of support and resistance levels provided in our previous report:
Rationale:
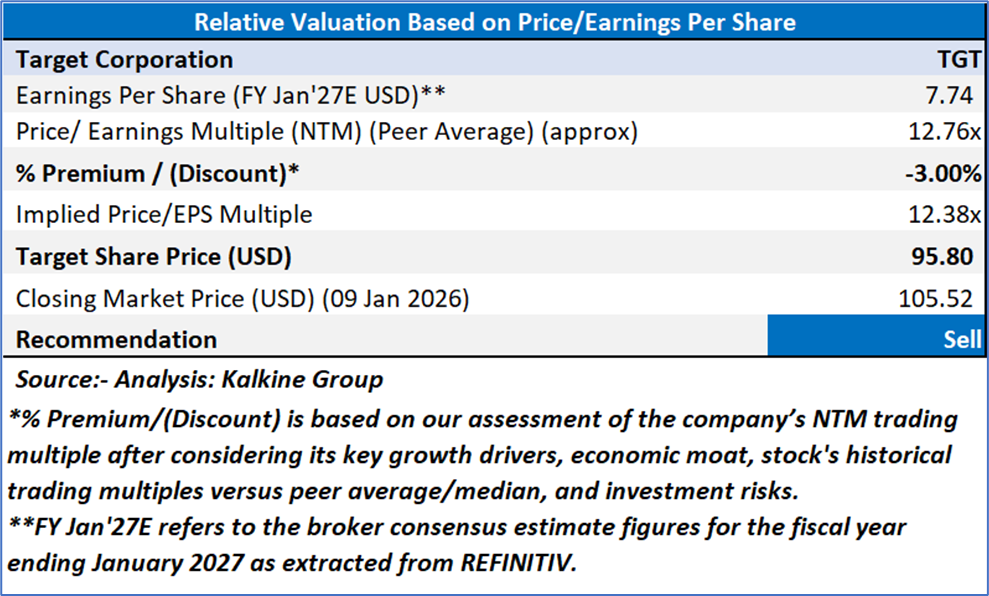
Valuation (Using P/E Multiple)
Share Price Chart
Conclusion
Target’s recent performance reflects a challenging operating environment marked by sustained pressure on discretionary demand, margin headwinds, and elevated execution risk. Comparable sales remain negative, driven by weak store traffic and softness in categories such as Home and Apparel, while increased markdowns have constrained gross margins. Although cost restructuring and operational initiatives are underway, they have introduced near-term expense pressure and weighed on earnings. With adjusted EPS declining year-on-year and management guiding cautiously amid volatile consumer behavior, the company has yet to demonstrate a clear and durable return to profitable growth.
Moreover, Target’s expansion of its wellness assortment by 30% for 2026, supported by the introduction of thousands of new, affordable and on-trend products and reinforced by promotional initiatives such as Target Wellness Week, represents a near-term positive catalyst that could drive investor optimism and share price appreciation. Given this potential sentiment-driven upside and the stock’s sensitivity to category-specific growth narratives, a "Sell" recommendation on Target Corporation (NYSE: TGT) has been given at the closing market price of USD 105.52 as on 09 January 2026.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is 09 January 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Note 6: Dividend Yield may vary as per the stock price movement.
Kalkine Equities LLC, with Delaware File Number 4697384, Foreign Qualification Registration in California File Number 202109211078, and Texas File Number 805521396, is authorized to provide general advice only. The information on https://kalkine.com/ does not take into account any of your investment objectives, financial situation or needs. You should consider the appropriateness of advice taking into account your own objectives, financial situation and needs and seek independent financial advice before making any financial decisions. The link to our Terms and Conditions and Privacy Policy has been provided for your reference. On the date of publishing the reports (mentioned on the website), employees and/or associates of Kalkine do not hold positions in any of the stocks covered on the website. These stocks can change any time and readers of the reports should not consider these stocks as advice or recommendations later.
Past performance is not a reliable indicator of future performance.
 Please wait processing your request...