
 CA
 NZ
 UK
 AU
 IND

 US
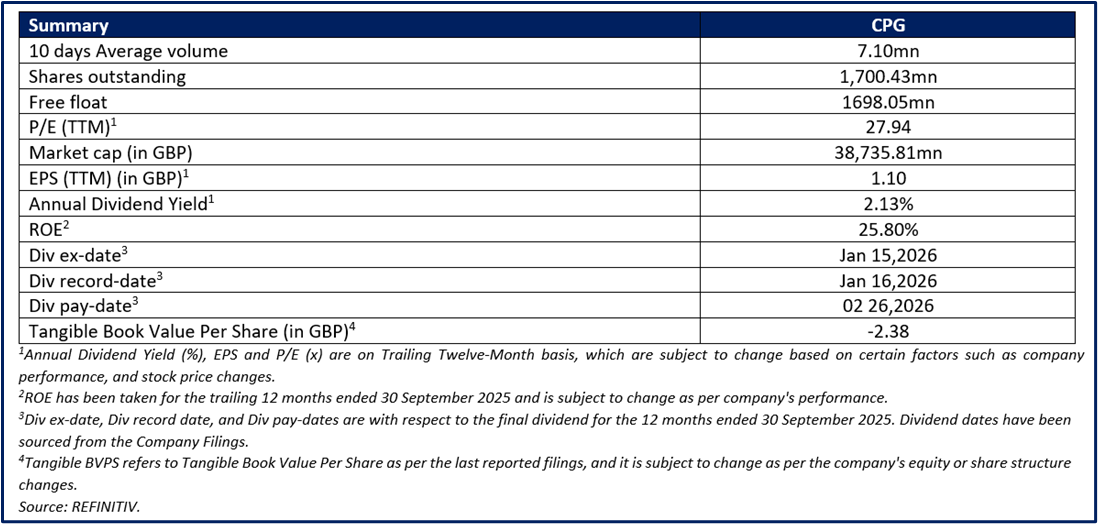
Compass Group PLC
Compass Group PLC (LSE: CPG) is an FTSE 100 index-listed, United Kingdom-based non-trading investment holding company. The Company is engaged in providing food and support services. The Company has three segments: North America, Europe, and Rest of World.
Key Recommendation Rationale – Sell at GBX 2,278.00
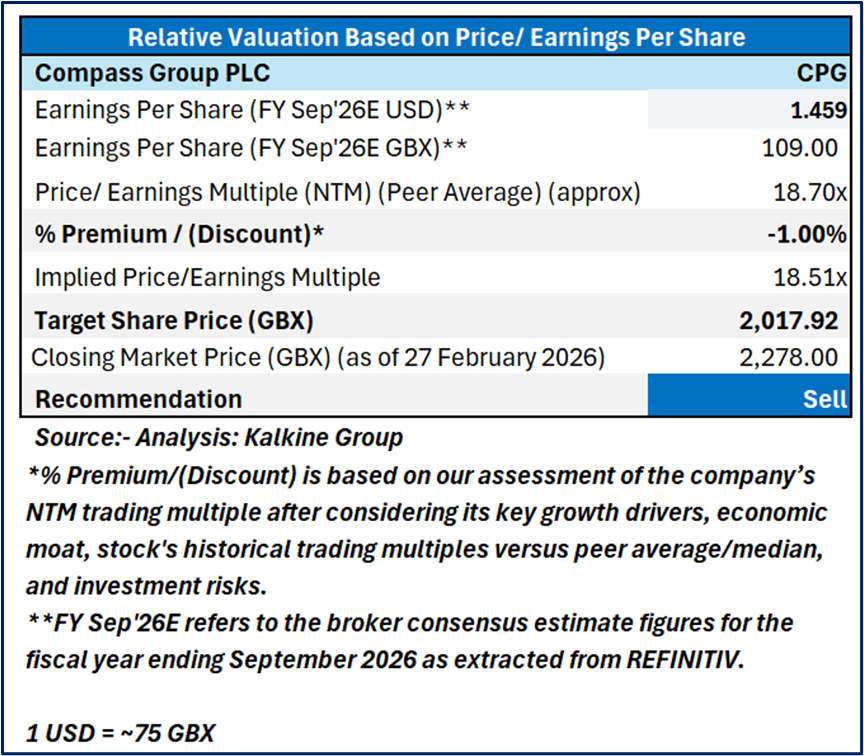
Valuation Methodology: Price/ Earnings Approach
Share Price Chart
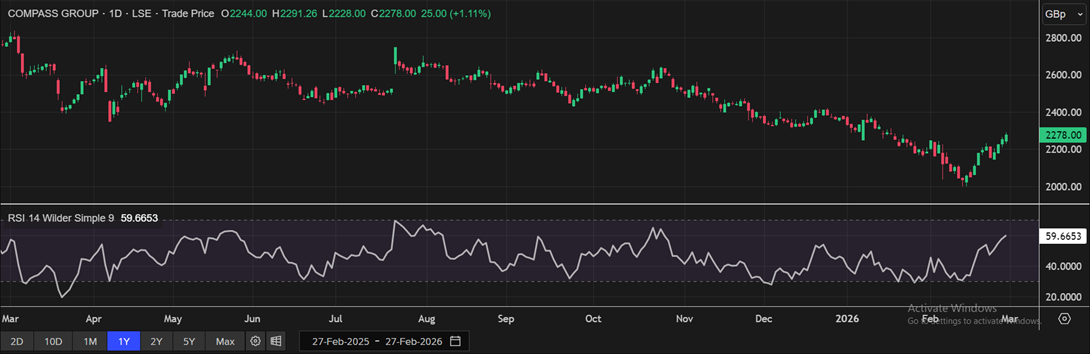
One Year Technical Chart (February 27, 2026) Source: REFINITIV
Conclusion
The USD 1.7bn Vermaat acquisition carries high integration risk, pressuring ROIC if cultural hurdles delay synergies. Cooling pricing power removes a key revenue tailwind, making growth reliant on volumes. FX volatility persists despite the currency switch, muddying true performance. Meanwhile, overexposure to cyclical sectors like B&I leaves growth vulnerable to macroeconomic downturns.
For conducting the valuation, the following peers have been considered: Fuller Smith & Turner PLC (LSE: FSTA), SSP Group PLC (LSE: SSPG), etc
Given its current trading levels, the recent strategic investments and partnerships, relative valuation, and associated risks, it is prudent to exit the stock at the current levels.
Hence, a ‘Sell’ recommendation is given on the stock at the Closing Market Price of GBX 2,278.00 as of 27 February 2026.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance levels is 27 February 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Kalkine Equities LLC, with Delaware File Number 4697384, Foreign Qualification Registration in California File Number 202109211078, and Texas File Number 805521396, is authorized to provide general advice only. The information on https://kalkine.com/ does not take into account any of your investment objectives, financial situation or needs. You should consider the appropriateness of advice taking into account your own objectives, financial situation and needs and seek independent financial advice before making any financial decisions. The link to our Terms and Conditions and Privacy Policy has been provided for your reference. On the date of publishing the reports (mentioned on the website), employees and/or associates of Kalkine do not hold positions in any of the stocks covered on the website. These stocks can change any time and readers of the reports should not consider these stocks as advice or recommendations later.
Past performance is not a reliable indicator of future performance.
 Please wait processing your request...