Kalkine’s Global Travel & Leisure Report offers a comprehensive view of the key companies and evolving trends across the travel value chain covering countries including US, Canada, Australia, UK, and New Zealand. This includes airlines, hospitality chains, digital travel platforms, as well as the rapidly growing leisure, entertainment, and gaming segments that are redefining the way people engage with travel experiences.

Airline Service and Cargo Market: A Dynamic Growth Trajectory:
- Global aviation revenues reached ~USD 970–990 billion in 2024, with passenger traffic recovering to ~102% of 2019 levels, signaling a fully normalized demand environment.
- 2025 passenger demand is projected to grow ~5–6% YoY, while aircraft delivery delays keep supply tight, supporting stronger fares and load factors.
- North America remains the most profitable region, generating over 60% of global airline net income, driven by strong U.S. leisure travel and diversified revenue models.
- Air cargo volumes are expected to grow ~4% YoY in 2025, with e-commerce–driven demand benefiting carriers with dedicated freighters—relevant for SNCY’s Amazon-based cargo operations.
- Fuel costs remain elevated at ~USD 110–120/bbl equivalent for 2025, maintaining pressure on margins and increasing the competitive advantage of low-cost and hybrid carriers with efficient cost structures.


- 2020 – Industry Collapse and Cargo Becomes the Lifeline: The aviation sector suffered an unprecedented contraction, with global passenger traffic down ~65% and airline losses exceeding USD 130 billion, driven by border closures and grounded fleets. Air cargo, supported by booming e-commerce and supply-chain bottlenecks, grew to over 35% of total airline revenue, which is its highest share in history. Cargo yields surged more than 40%, freighter capacity ran at peak utilization, and dedicated cargo operators became essential to global trade continuity.
- 2021 – Domestic Recovery Begins, Cargo Demand Stays Elevated: Passenger demand recovered to ~50% of 2019 levels, led by U.S. leisure travel, with TSA throughput rising steadily from March onward. Airlines restructured fleets, renegotiated leases, and pushed digital ticketing and contactless operations. Cargo volumes grew an additional 6–8%, benefiting from persistent supply-chain disruptions, tight belly capacity, and e-commerce growth exceeding 20% annually. Hybrid carriers with freighter arrangements, like Sun Country, began emerging as operationally advantaged models.
- 2022 – International Reopening, Strong Revenue Rebound, Supply Constraints: Global passenger demand climbed to ~70–75% of 2019, with strong gains in Europe and early APAC reopening phases. Airline revenues recovered to approximately USD 780–800 billion, and load factors improved to 80–81%, though staffing shortages and aircraft delivery delays constrained supply. Cargo performance peaked, with yields still ~25–30% above 2019, supported by resilient e-commerce and high-value goods transport. North America became the first region to exceed its pre-pandemic financial performance.
- 2023 – Full Passenger Recovery and Cargo Normalization at a Higher Base: Passenger traffic returned to 100% of 2019 levels, and global airline revenue exceeded USD 900 billion, marking full top-line recovery. Load factors averaged ~83–84%, among the highest ever recorded. Cargo volumes stabilized as supply chains normalized but yields remained 5–10% above pre-pandemic levels, aided by structural e-commerce demand. Fleet shortages—driven by Boeing/Airbus certification delays—kept supply tight, supporting fare strength and improving unit economics.
- 2024 – Profitability Consolidation and Hybrid Models Gain Momentum: The industry generated ~USD 970–990 billion in revenue and recorded the strongest global profitability since 2010, with North America producing more than 60% of world airline net income. Passenger demand grew ~11%, while capacity increased more slowly due to aircraft delays and pilot shortages, sustaining high load factors. Air cargo revenue normalized but remained above 2019 levels, with e-commerce expanding 15–18% YoY. Airlines increasingly diversified into loyalty monetization, cargo operations, charter services, and ancillary revenue—directly mirroring SNCY’s strategic mix.
- 2025 – Moderation, Structural Tightness, and Strength in Cargo Partnerships: Passenger demand is projected to grow 5–6%, while load factors remain elevated due to continued aircraft delivery constraints. Jet-fuel prices stabilize around USD 110–120/bbl equivalent, keeping cost discipline paramount. Cargo volumes are forecast to rise ~4%, driven by Amazon-style contract flying and cross-border express shipping. North America remains the profit engine of global aviation, supported by strong leisure demand, robust ancillary revenue streams, and stable cargo economics. The industry shifts from rebound to steady, structurally supported growth, favoring flexible operators with diversified revenue—an environment well-suited for Sun Country’s scheduled, charter, and cargo tri-model strategy.
Kalkine’s Global Travel & Leisure Report covers the Investment Highlights, Key Financial Metrics, Risks, Technical Analysis along with the Valuation, Target Price, and Recommendation on Southwest Airlines Company (NYSE: LUV).
Section 1: Company Overview and Fundamentals Insights
Company Overview: Southwest Airlines Co. (Southwest) (NYSE: LUV) operates Southwest Airlines, a passenger airline that provides scheduled air transportation in the United States and near-international markets. The Company's fare products include four categories: Wanna Get Away, Wanna Get Away Plus, Anytime, and Business Select to provide customers options when choosing a fare. It also offers ancillary services, such as EarlyBird Check-In, Upgraded Boarding, and transportation of pets and unaccompanied minors, in accordance with Southwest’s respective policies.
Kalkine’s Global Travel and Leisure Report covers the Investment Highlights, Key Financial Metrics, Risks, and Technical Analysis along with the Valuation, Target Price, and Recommendation on the stock.
1.2 The Key Positives, Negatives, Investment Highlights, and Risks
1.3 Top 10 Shareholders:
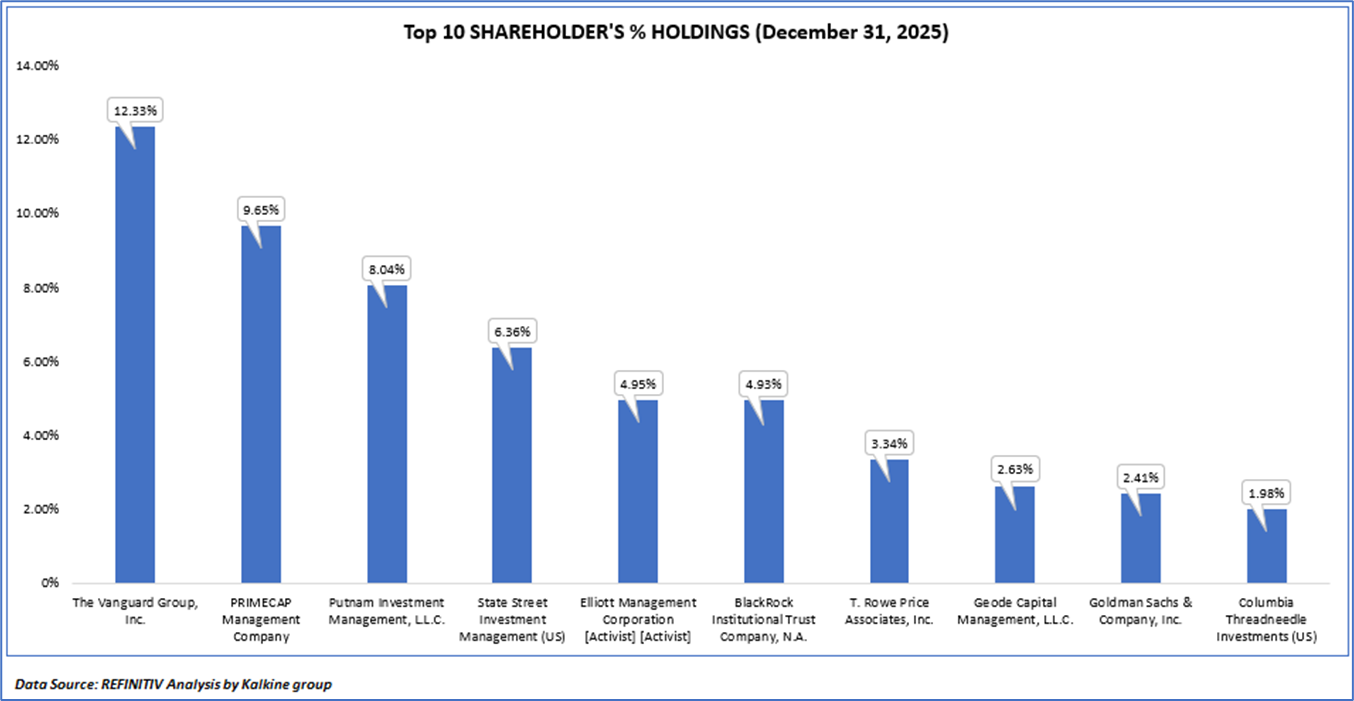
The top 10 shareholders together form ~56.63% of the total shareholding, signifying concentrated holding. The Vanguard Group, Inc and PRIMECAP Management Company hold maximum stakes of 12.33% and 9.65%, respectively.
1.4 Key Metrics:
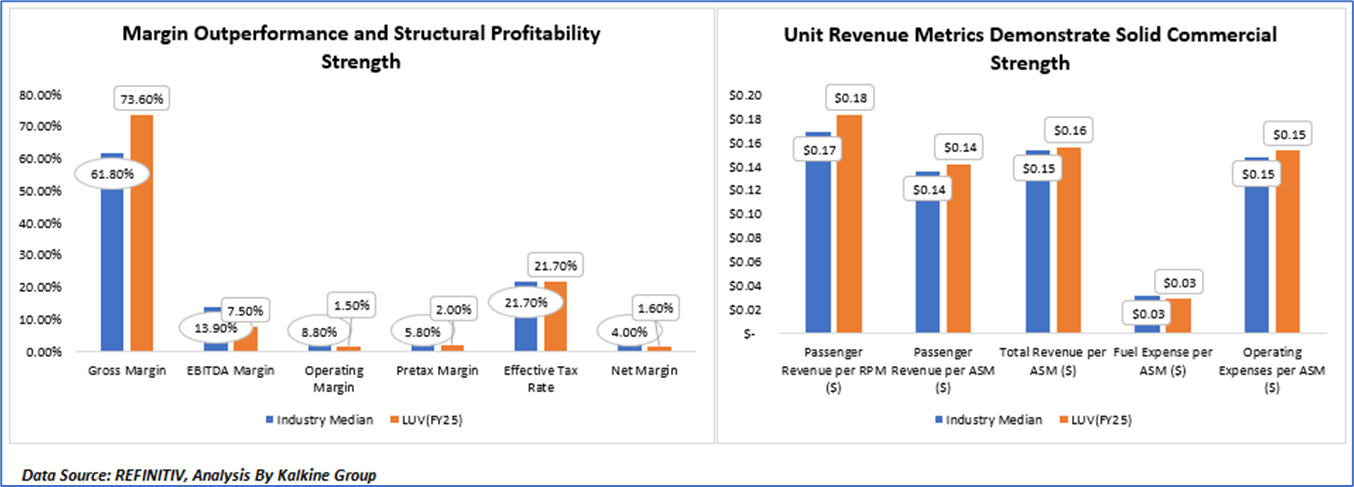
- Revenue Quality and Gross Margin Outperformance: Southwest Airlines reported a Gross Margin of 73.60% in FY2025, materially above the industry median of 61.80%, indicating superior top-line revenue retention and comparatively efficient direct cost absorption at the gross profit level. This outperformance likely reflects the company’s strong domestic network scale, effective fare monetization initiatives, healthy ancillary revenue conversion, and disciplined fuel and labor management within direct operating categories. The result suggests that Southwest continues to benefit from a structurally attractive commercial platform capable of generating stronger gross profitability than many peers despite operating in a competitive fare environment.
- Below-Median EBITDA and Operating Margin Profile: Despite strong gross margin performance, Southwest’s profitability below the gross profit line remained comparatively subdued. FY2025 EBITDA Margin of 7.50% trailed the industry median of 13.90%, while Operating Margin of 1.50% was significantly below the industry median of 8.80%. This divergence indicates that corporate overhead, labor inflation, technology investment, transformation-related spending, and broader operating cost burdens materially compressed earnings conversion. It also implies that while the company retains pricing strength, the full benefit of revenue generation has not yet translated into normalized operating leverage. This gap may represent both a current weakness and a future opportunity if management successfully executes cost restructuring and margin expansion plans.
- Pretax Profitability and Net Earnings Conversion: Southwest generated a Pretax Margin of 2.00%, below the industry median of 5.80%, while Net Margin of 1.60% also lagged the industry median of 4.00%. The company’s Effective Tax Rate of 21.70% was in line with the industry median, indicating that earnings underperformance was not tax-related but principally operational in nature. The data suggests that interest costs, depreciation, elevated personnel expenses, and strategic reinvestment initiatives likely constrained bottom-line conversion. Consequently, Southwest’s earnings profile remains in recovery mode rather than peak-cycle profitability.
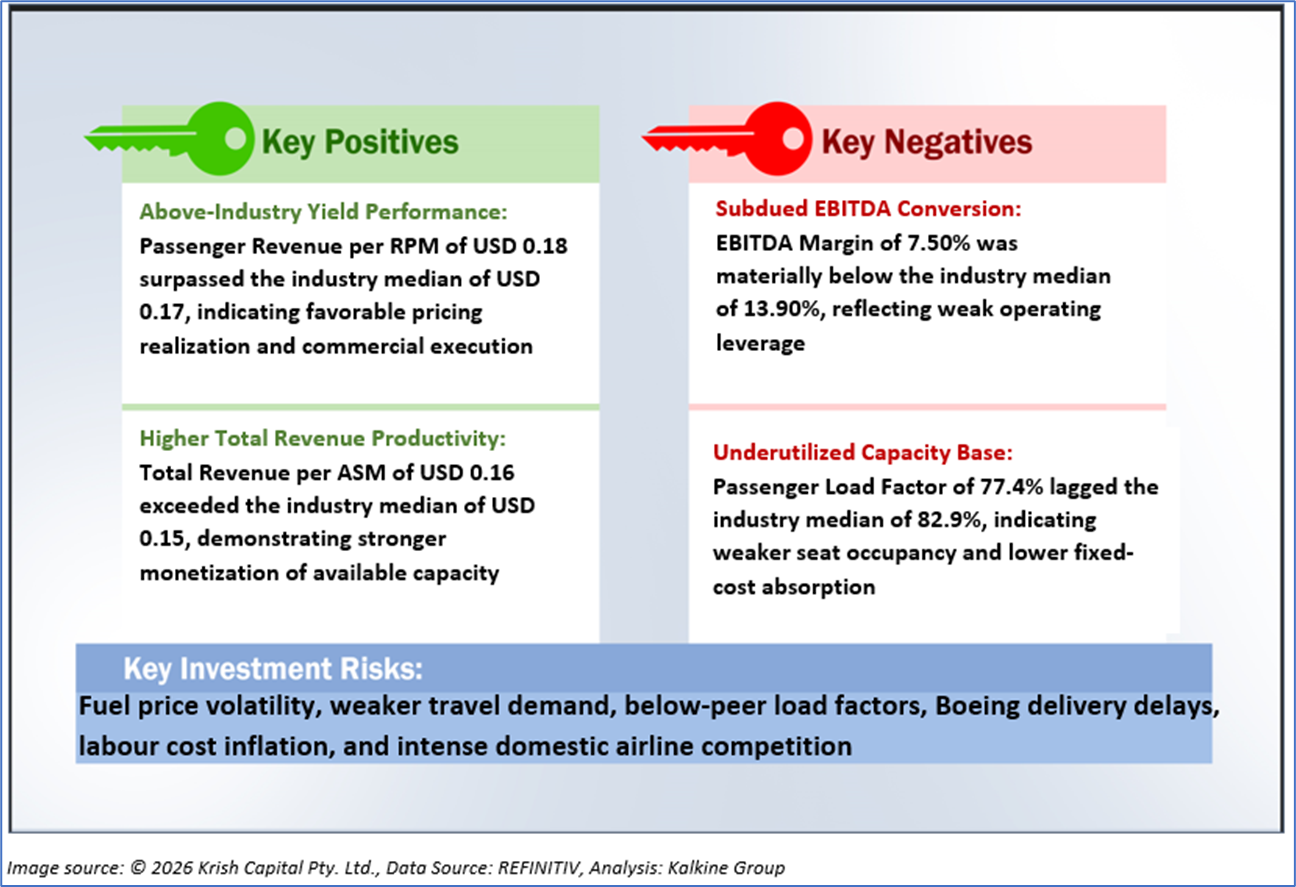
- Unit Revenue Metrics Demonstrate Solid Commercial Strength: From a unit revenue standpoint, Southwest displayed encouraging relative performance. Passenger Revenue per Revenue Passenger Mile (RPM) of USD 0.18 exceeded the industry median of USD 0.17, indicating favorable pricing realization and yield management. Total Revenue per Available Seat Mile (ASM) of USD 0.16 also surpassed the industry median of USD 0.15, reflecting stronger overall monetization of seat capacity, inclusive of ancillary and loyalty-related revenue streams. Passenger Revenue per ASM of USD 0.14 was in line with the industry median, suggesting broadly competitive network revenue productivity. Collectively, these metrics imply that Southwest’s demand environment and commercial execution remain comparatively sound.
- Load Factor Weakness and Utilization Opportunity: Southwest’s principal operational underperformance appears in capacity utilization, with a Passenger Load Factor of 77.4%, materially below the industry median of 82.9%. This indicates lower seat occupancy relative to peers and may reflect network repositioning, schedule optimization efforts, domestic market competition, or a transitional product strategy during the year. Importantly, Fuel Expense per ASM of USD 0.03 and Operating Expenses per ASM of USD 0.15 were both aligned with industry medians, suggesting cost inefficiency was not primarily driven by unit expense inflation but by weaker fixed-cost absorption due to lower load factors. If Southwest improves aircraft utilization and passenger mix while preserving current unit revenue trends, margin recovery potential could be significant.
Section 2: Business Updates, Financial and Operational Highlights
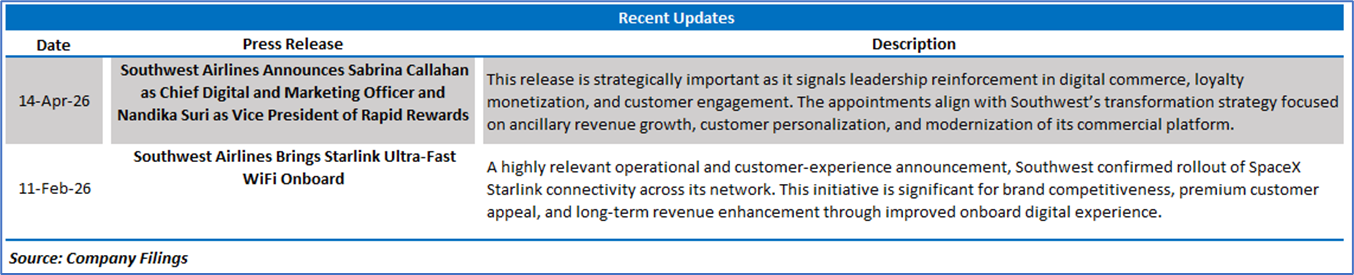
2.1 Recent Business Updates:
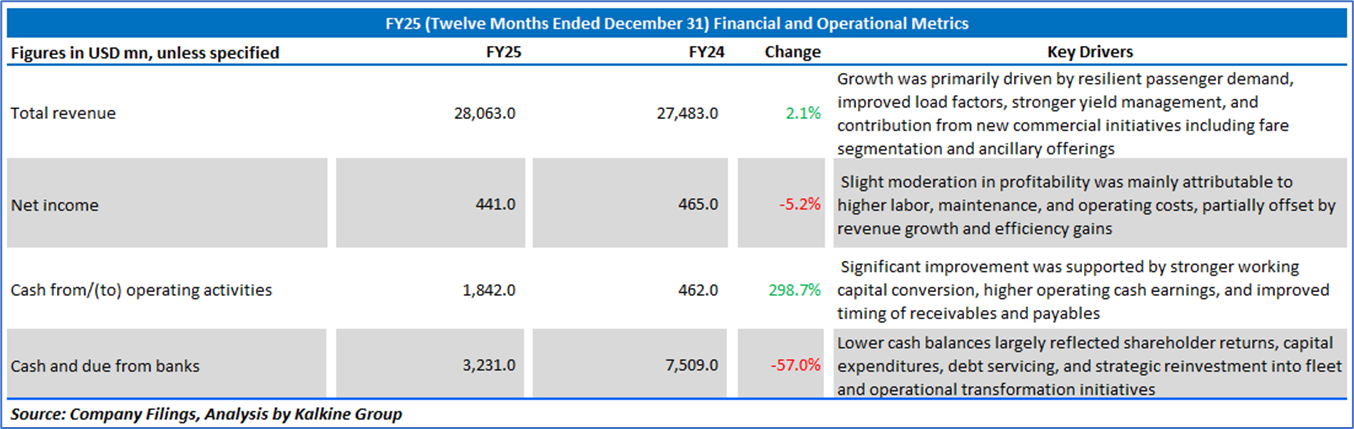
2.2 FY25 Results Highlights (Twelve Months Ended December 31, 2025): Below are some key financial highlights:
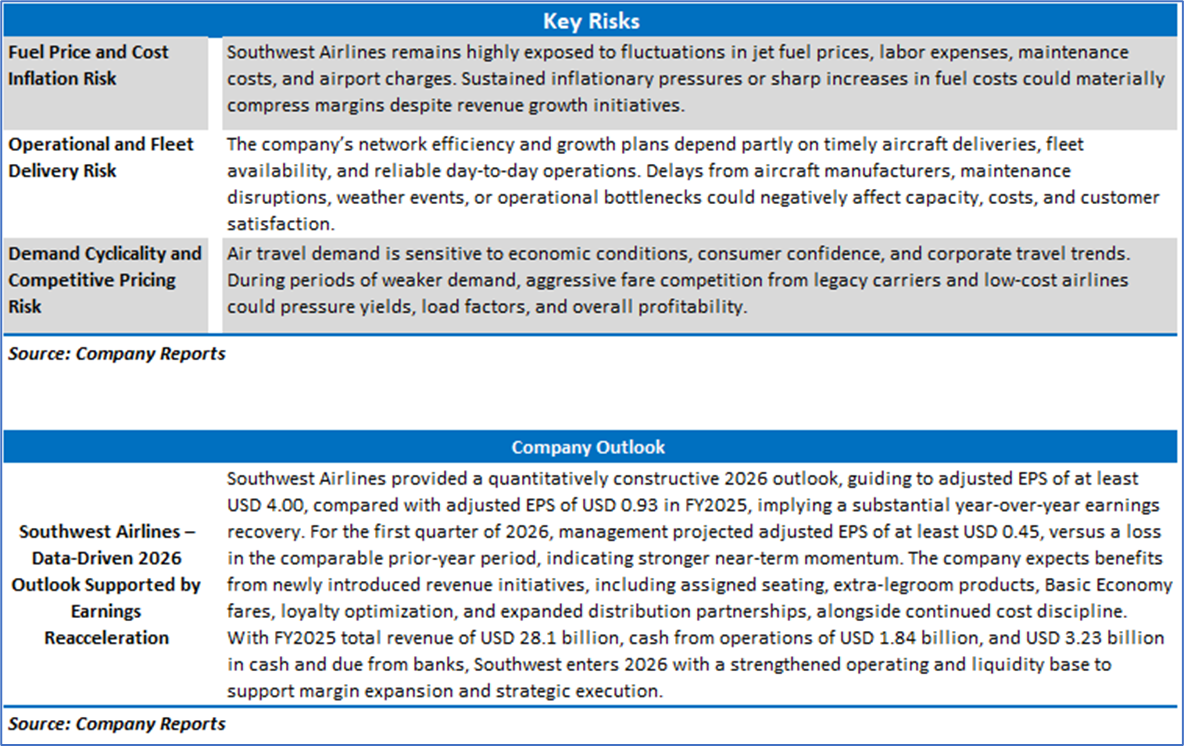
Section 3: Key Risks and Outlook:
Section 4: Stock Recommendation Summary
4.1 Price Performance and Technical Summary
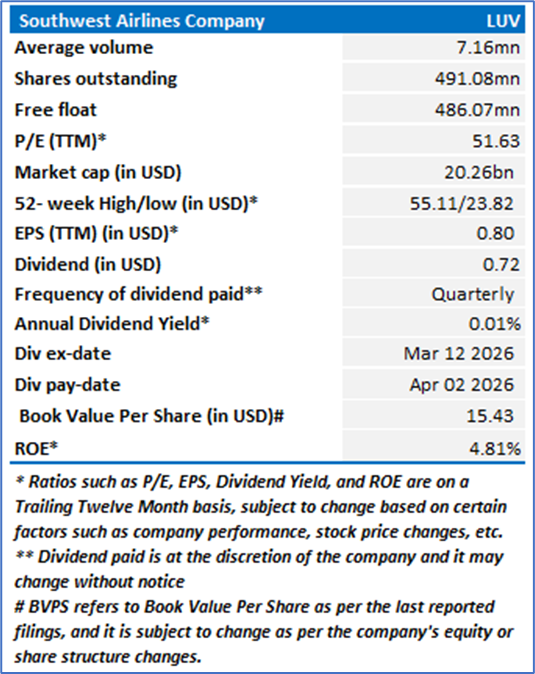
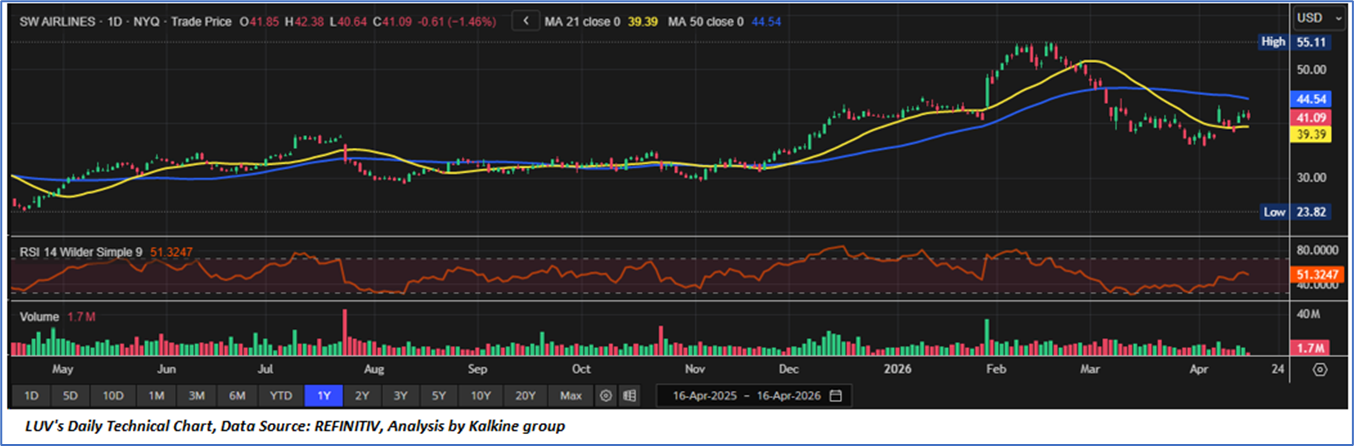
- Constructive Recovery Attempt Within a Broader Intermediate Uptrend: Southwest Airlines Co. (NYSE: LUV) is currently trading at USD 41.09, reflecting a developing recovery phase following the sharp pullback from its recent peak of USD 55.11. Over the broader one-year horizon, the stock continues to exhibit an improving medium-term structure characterized by higher lows from the April 2025 base near USD 23.82, indicating that the primary trend remains constructive despite recent volatility. The rebound from the March correction zone suggests renewed buying interest, although the stock remains in a transitional phase between recovery and full trend resumption.
- Moving Average Configuration and Momentum Dynamics: LUV is presently trading above the 21-day moving average of USD 39.39, but below the 50-day moving average of USD 44.54, creating a mixed near-term technical configuration. Holding above the shorter-term average indicates improving short-term sentiment, while the inability to reclaim the 50-day average confirms that medium-term resistance remains active. The 14-day Relative Strength Index is near 32, modestly above neutral territory, suggesting balanced momentum with a slight bullish bias. Importantly, RSI has recovered from prior weaker readings, implying downside momentum has eased and accumulation may be re-emerging.
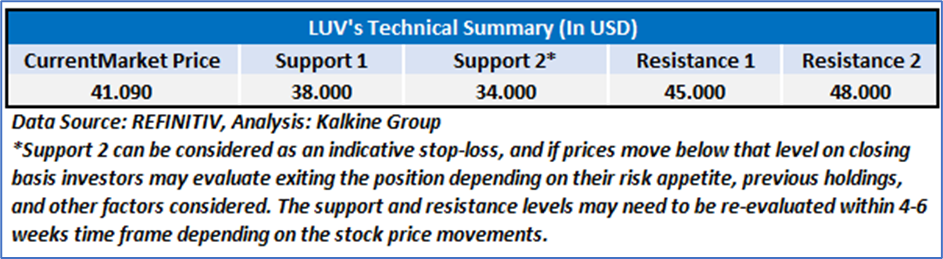
- Key Levels, Breakout Triggers and Tactical Outlook: Immediate support is established near the USD 39.40–40.00 region, aligned with the 21-day moving average, followed by stronger structural support near USD 36.50–37.00 where previous consolidation demand emerged. On the upside, initial resistance is located at the 50-day moving average near USD 44.54, with a more significant breakout zone in the USD 47.00–48.50 A decisive move above these levels would materially strengthen the technical outlook and reopen the path toward the prior high near USD 55.11. Conversely, failure to sustain current support could extend the consolidation process. Overall, LUV appears technically neutral-to-constructive, with improving momentum but requiring confirmation through a break above medium-term resistance.
4.2 Fundamental Valuation
Valuation Methodology: Price/Earnings Multiple Based Relative Valuation (Illustrative)
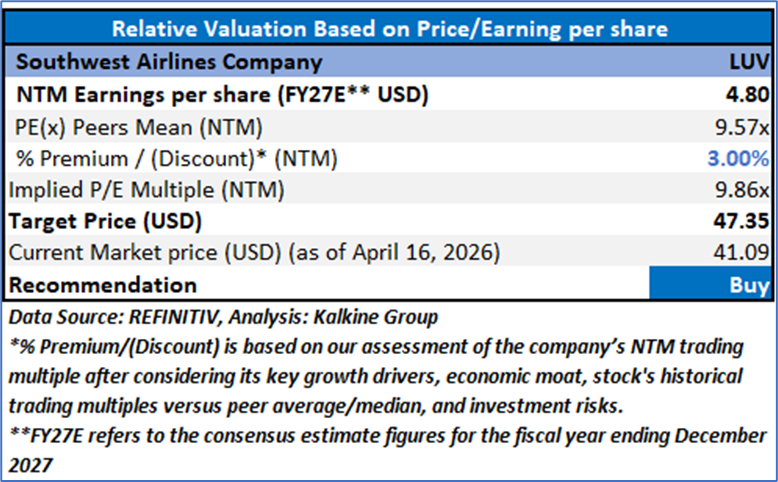
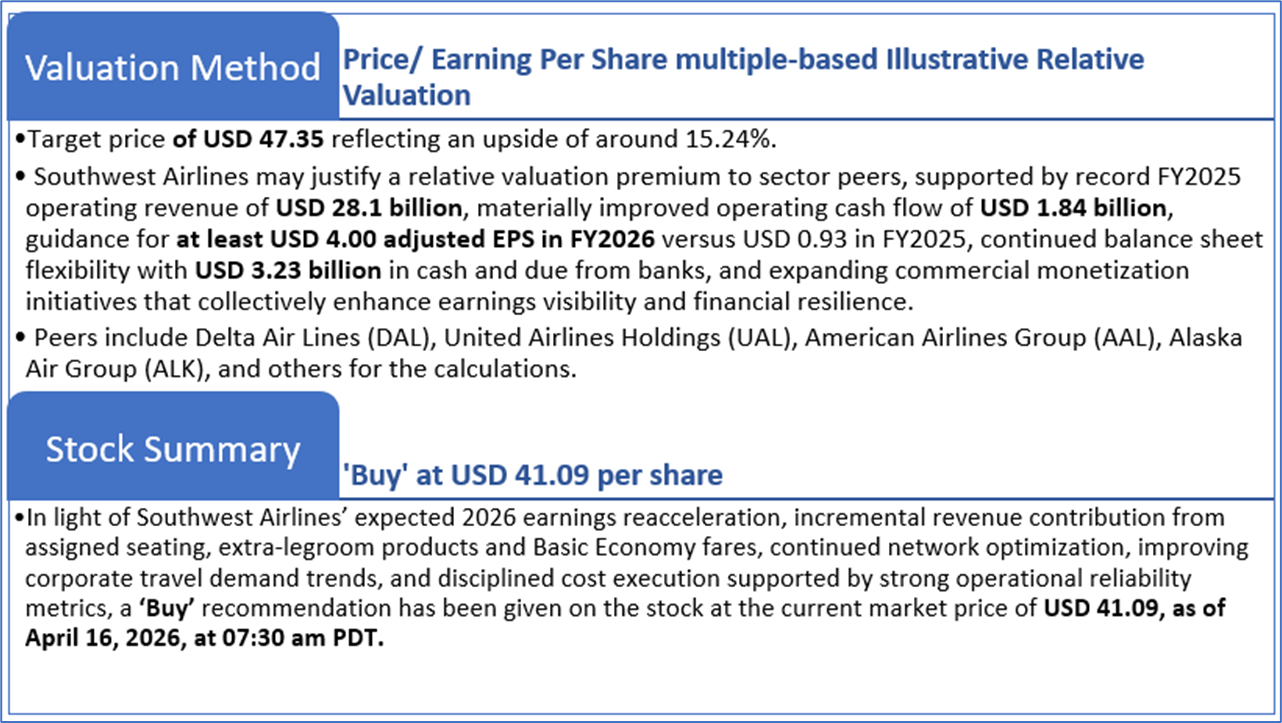
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and geopolitical tensions prevailing. Therefore, it is prudent to follow a cautious approach while investing.
Note 1: Past performance is neither an indicator nor a guarantee of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance levels is 16 April 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Dividend Yield may vary as per the stock price movement.
Note 5: Kalkine reports are prepared based on the stock prices captured either from REFINITIV or Trading View. Typically, REFINITIV or Trading View may reflect stock prices with a delay which could be a lag of 25-30 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.
Technical Indicators Defined: -
Support: A level at which the stock prices tend to find support if they are falling, and a downtrend may take a pause backed by demand or buying interest. Support 1 refers to the nearby support level for the stock and if the price breaches the level, then Support 2 may act as the crucial support level for the stock.
Resistance: A level at which the stock prices tend to find resistance when they are rising, and an uptrend may take a pause due to profit booking or selling interest. Resistance 1 refers to the nearby resistance level for the stock and if the price surpasses the level, then Resistance 2 may act as the crucial resistance level for the stock.
Stop-loss: It is a level to protect further losses in case of unfavourable movement in the stock prices.
Past performance is not a reliable indicator of future performance.

 CA
 NZ
 UK
 AU
 IND

 US

 Please wait processing your request...