
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
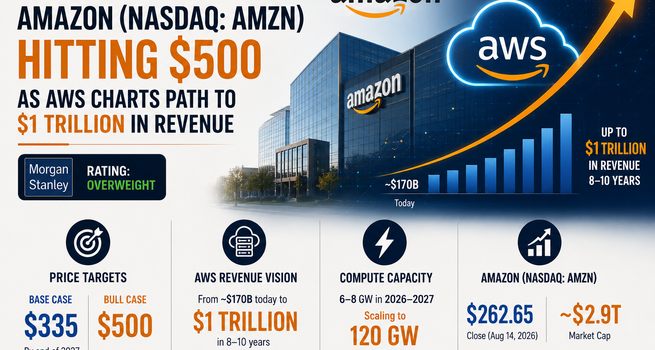
- Morgan Stanley rates Amazon.com Inc. (NASDAQ: AMZN) Overweight, with a base case price target of $335 and a bull case of $500 by year-end 2027.
- The firm sees AWS Revenue scaling from roughly $170 billion annualized today to as much as $1 trillion over 8-10 years.
- Compute capacity remains the key constraint, with AWS estimated to add 6-8 gigawatts in 2026-2027 and scale to 120 gigawatts by 2035.
- Amazon shares closed at $262.65 on August 14, 2026, giving the company a market Capitalization of roughly $2.9 trillion.
Morgan Stanley analyst Brian Nowak laid out a path for Amazon.com Inc. (NASDAQ: AMZN) shares to reach $500 by the end of 2027, driven by Amazon Web Services scaling toward $1 trillion in annual revenue over the next 8 to 10 years, a roughly sixfold increase from its current run rate of about $170 billion.
A Trillion-Dollar Vision, Straight From Amazon
Morgan Stanley's report, titled "AWS's Path to $1 Trillion of Revenue and How AMZN Shares Can Double," points to Amazon's own Q2 2026 Earnings commentary as reinforcing this thesis. Management said it long believed AWS could become a few hundred billion dollar revenue business, and now believes it could be at least double that, and very possibly a $1 trillion annual revenue Business with appealing free Cash Flow and returns on invested capital. Management also compared the buildout to the early Cloud Computing era, noting that AI margins and returns are tracking what core AWS showed at the same stage of evolution, and possibly a little ahead.
That framing matters because it links AWS's current AI-driven acceleration to a business Amazon has already scaled successfully once before, giving Morgan Stanley a historical reference point for how the current buildout might unfold, even though the firm notes that Demand is building faster this time than it did during the first cloud computing wave.
Compute Capacity Is the Gating Factor
Morgan Stanley's base case assumes Amazon adds roughly 8 gigawatts of compute capacity per year going forward, with the firm estimating AWS will bring on 6 to 8 gigawatts in 2026 and 2027 combined, scaling toward 120 gigawatts by 2035 as AWS growth accelerates toward 40%. The firm's base case supports a $335 price target, about 30% above Amazon's August 14 closing price of $262.65, while the bull scenario, in which AWS delivers on the full $1 trillion vision alongside roughly $500 billion in company-wide EBIT, supports a $500 share price target by the end of 2027.
Morgan Stanley acknowledges limited visibility into exactly how much capacity AWS will bring online beyond 2027, citing unknowns around server and rack purchase volumes, improving power draws per rack, evolving regulatory questions, and physical limits to how quickly new data centers can be built, including labor, construction, and power availability. Even accounting for that uncertainty, the firm views Amazon as executing at an organized and rapid pace in bringing on its current capacity.
What the Numbers Imply About Amazon's Other Businesses
A separate back-of-envelope valuation exercise applied to Morgan Stanley's forecast illustrates the scale of the opportunity. Using the firm's projected $530 billion in AWS revenue by 2030, a 25% net margin, and a 25 times earnings multiple implies a future AWS value of roughly $3.3 trillion, which discounts back to about $2.2 trillion today at a 10% annual discount rate. Against Amazon's current total market capitalization of roughly $2.8 trillion, that would imply the market is valuing all of Amazon's other businesses, which generated roughly $630 billion in revenue, at only about $600 billion combined, a multiple well below what standalone retailers typically command.


 Nov 13, 2026





 Please wait processing your request...