
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Lam Research closed at USD 369.34 on June 16, down 5.03%, with volume near 11.62 million shares.
LRCX traded at USD 379.98 pre-market on June 17, up 2.88% from the prior close.
• Analyst upgrades and a stronger wafer-fabrication equipment outlook supported the rebound.
Lam Research Corporation (NASDAQ:LRCX) rose 2.88% in June 17 pre-market trading to USD 379.98 after closing at USD 369.34 on June 16.
The recovery followed a broad semiconductor-sector selloff rather than a clear deterioration in Lam’s operating outlook. Investors had rotated out of technology shares ahead of the Federal Reserve meeting, pushing chip-equipment stocks sharply lower.
Analyst actions helped restore confidence. Citigroup reportedly raised its price target to USD 450 from USD 315, while Rothschild and Co Redburn lifted its target to USD 420 from USD 305. Both firms maintained positive ratings.
Lam’s management has also increased its 2026 wafer-fabrication equipment market estimate to roughly USD 140 billion, reflecting stronger AI-driven semiconductor capital expenditure.
Company and Industry Context
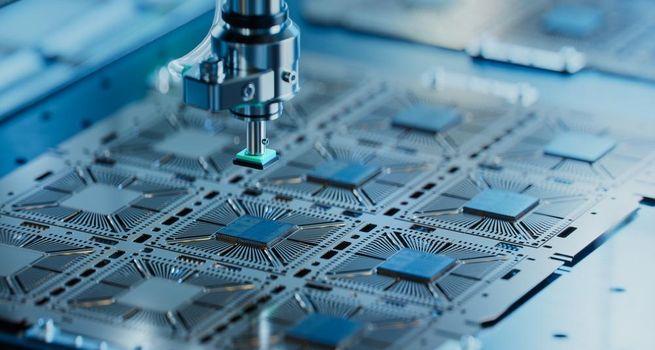
Lam supplies equipment used in deposition, etching and other critical semiconductor manufacturing processes. Its customers include leading memory, logic and foundry manufacturers.
AI infrastructure demand is increasing investment in advanced logic, high-bandwidth memory and complex packaging. That supports equipment demand, although spending remains cyclical and sensitive to customer capital budgets.
Valuation and Risk
At the latest close, Lam had a market capitalisation of about USD 461.89 billion, a P/E ratio near 69.82 and EPS of approximately USD 5.29.
The valuation assumes sustained equipment demand and strong earnings growth. Risks include delayed customer spending, weaker memory investment and geopolitical restrictions affecting semiconductor equipment sales.
What Investors Are Watching Next
Investors will monitor foundry and memory capital expenditure, China exposure, order growth and management’s USD 140 billion equipment-market forecast.
Conclusion
Lam’s pre-market rebound reflects renewed confidence in semiconductor manufacturing investment after a sector-led decline. The sustainability of the move will depend on customer spending and order visibility.

 Nov 02, 2026
 Please wait processing your request...