
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
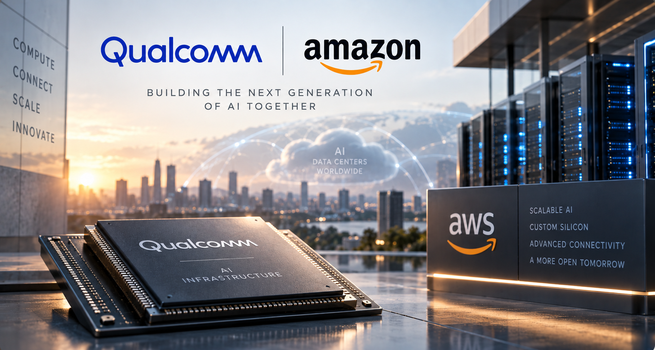
- Qualcomm and Amazon Web Services announced a multi-generation collaboration on custom silicon and optical connectivity for AI Data Center infrastructure.
- The arrangement is structured through a Warrant tied to purchase commitments of up to $60 billion, rather than a conventional Supply contract.
- The structure echoes a similar warrant-based custom-chip deal Marvell struck with Alphabet weeks earlier, pointing to a broader industry pattern in hyperscaler chip financing.
- The announcement builds on Qualcomm's earlier data center push, including its Dragonfly C1000 CPU and a fiscal 2029 data center Revenue target of $15 billion.
- The deal adds Qualcomm to a widening field of chipmakers contesting the AI infrastructure buildout alongside GPU incumbent Nvidia.
A Structural Bet on AI Inference
Qualcomm Incorporated (NASDAQ:QCOM) and Amazon (NASDAQ:AMZN) have announced a multi-generation collaboration to develop customized silicon for AI data center infrastructure, with an explicit focus on AI inference, the process of running trained models in production rather than Training them from scratch. The two companies will also jointly develop optical connectivity technology, including solutions extending to 1.6 terabits per second, aimed at the high-bandwidth interconnects large AI clusters increasingly depend on.
The announcement extends Qualcomm's effort to build a presence in data center computing beyond its traditional base in handset chipsets and wireless licensing. It follows the company's earlier disclosure of the Dragonfly C1000, a data center CPU built around agentic AI workloads and a power-efficiency thesis drawn from Qualcomm's mobile computing background. Under the new collaboration, Qualcomm also plans to deepen its own use of AWS infrastructure, including Amazon Bedrock, for chip design workflows, with the stated aim of shortening design cycles.
The optical connectivity component of the Partnership traces back to a more recent capability build-out. Qualcomm entered the high-speed optical interconnect space through its roughly $2.4 billion Acquisition of AlphaWave last year, a deal that also brought AlphaWave's chief executive into Qualcomm's fold to lead its data center chip business. That acquisition gives Qualcomm a technical basis for pairing compute silicon with connectivity products in a single offering, a combination few competitors in AI infrastructure can currently match.
How the Arrangement Is Structured
Rather than a conventional supply agreement, the collaboration is anchored by an Equity warrant. According to a regulatory filing, Qualcomm issued Amazon the right to acquire shares at a fixed exercise price, with vesting tied to the execution of commercial arrangements, the Placement of binding purchase orders, and actual purchases of Qualcomm's server chip products, technology, systems, and Manufacturing services. The structure caps eligible purchases at a defined ceiling, with an initial Tranche of shares vesting immediately based on early commitments.
This mechanism aligns the two companies' incentives without requiring Amazon to commit cash upfront, while giving Qualcomm a direct stake in ensuring the partnership converts into actual procurement rather than remaining aspirational. It also signals a broader shift in how large technology buyers are financing chip supply relationships, increasingly through equity-linked structures rather than fixed-price contracts alone. Qualcomm's arrangement is not an isolated case: Marvell Technology (NASDAQ:MRVL) reached a comparable custom-chip agreement with Alphabet (NASDAQ:GOOGL) weeks earlier, issuing Google a stock warrant valued at roughly $12.2 billion, suggesting hyperscalers are converging on warrant-based structures as a preferred way to lock in chip supply while sharing execution risk with their silicon partners.
Why Inference Is the Battleground
Inference has become the fastest-growing segment of AI infrastructure spending as enterprises move from experimenting with AI models to deploying them at scale. Where training workloads favor GPU-dense clusters optimized for parallel computation, inference at scale rewards power efficiency and cost per query, a different set of engineering priorities. Qualcomm has consistently positioned its low-power mobile computing heritage as a structural advantage in this specific niche, distinct from the training-optimized architecture that has underpinned Nvidia's (NASDAQ:NVDA) dominance.
The broader data center CPU market is expanding as AI workloads generate Demand beyond GPUs alone, with industry projections pointing to roughly a doubling in market size by the end of the decade. Nvidia itself has acknowledged that CPU capacity is becoming a bottleneck in scaling agentic AI workflows, an admission that implicitly validates the opportunity chipmakers like Qualcomm are now pursuing.
Amazon is not a passive buyer in this dynamic. The company has spent recent years building out its own custom silicon lineup for AWS, a Business that had grown to an annualized revenue run rate above $25 billion by the end of the June quarter. That existing Investment underscores that the Qualcomm partnership supplements rather than replaces Amazon's internal chip ambitions, with the two efforts likely serving different workload profiles within AWS's infrastructure.
Strategic Implications for Qualcomm's Positioning
For a company whose revenue base has historically been concentrated in handset chipsets and licensing, a credible entry into AI data center infrastructure carries meaningful implications for its Long-term Growth outlook. Diversification into a higher-growth, less cyclical end market is the kind of structural shift that can support a re-rating over time, provided execution follows through with actual revenue recognition rather than remaining at the level of a strategic announcement. Amazon now joins Microsoft (NASDAQ:MSFT) and Meta (NASDAQ:META) among the hyperscaler customers backing Qualcomm's data center ambitions, giving the company a broadening base of cloud relationships rather than dependence on a single anchor customer.
That qualification matters. The warrant structure means near-term revenue impact will be gradual. Vesting depends on binding orders and actual purchases materializing across multiple product generations, so the $60 billion ceiling referenced in the filing represents a maximum potential scale of business rather than contracted revenue. The announcement should be read as a directional signal on positioning, not as a near-term catalyst for Qualcomm's Earnings trajectory.
Risks Worth Weighing
Execution risk is the primary consideration. Qualcomm is entering data center silicon against incumbents with established hyperscaler relationships and multi-year head starts in software ecosystem support, where switching costs and integration depth matter as much as raw chip performance. Recent guidance has also flagged Margin pressure from industry-wide memory price increases, and the company continues to face the eventual loss of its Apple (NASDAQ:AAPL) modem business alongside rising component costs and softer handset demand, underscoring that the core business still faces near-term headwinds this initiative has yet to offset.
Concentration risk sits alongside execution risk. A meaningful share of current hyperscaler capex is directed at AI workloads whose long-term return profile remains under active debate; a deceleration in that spending would pressure suppliers positioned around the buildout, Qualcomm included.
What This Means for Qualcomm's Trajectory
The Qualcomm-Amazon collaboration represents a structurally significant step in Qualcomm's diversification into AI infrastructure, pairing a warrant-based financing mechanism with a multi-generation roadmap spanning custom silicon and optical connectivity. It gives Qualcomm a credible foothold in the inference segment of the AI buildout and a tangible commercial relationship with one of the industry's largest Capital allocators. Whether the arrangement becomes a durable pillar of Qualcomm's revenue mix will depend on how quickly purchase commitments convert into binding orders, and on the company's ability to manage the transition without losing ground in its existing handset business.

 Nov 10, 2026
 Please wait processing your request...