
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
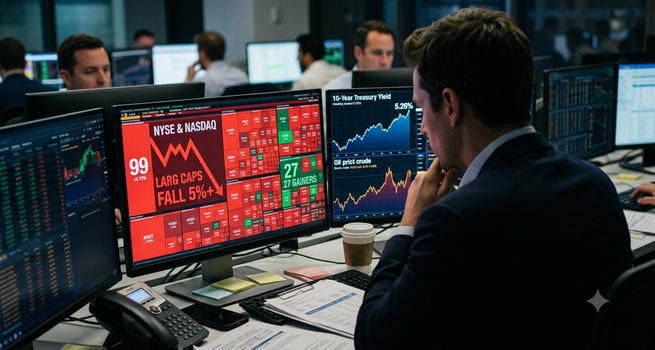
- Among stocks worth more than USD 1 billion, 99 fell 5% or more while only 27 gained 5% or more, a ratio of roughly 3.7 to 1.
- Selling was broad rather than extreme: 71 of the 99 decliners lost between 5% and 7%.
- 84 of the 99 decliners are also lower over the past month, while only 12 of the 27 gainers are higher over the month.
- Healthcare supplied 17 of the 27 large gainers, while decliners were spread evenly across mining, software, AI infrastructure, power and other sectors.
- The 10-year Treasury Yield climbed to about 5.26% to 5.27%, its highest level since 2007.
US stocks retreated on Monday, September 28, 2026, after a strong prior week. The Dow, S&P 500 and Nasdaq each fell by roughly 0.5% to 1.2%, with technology and Growth Stocks leading the decline.
Two screens of US-listed stocks with market capitalisations above USD 1 billion show the imbalance clearly. One captures every such stock that gained more than 5% in the session. The other captures every such stock that fell 5% or more. Together, they offer a useful view of market breadth, or how widely buying and selling pressure was distributed beneath the index level.
What Drove the Sell-Off
Three forces combined to push markets lower. The first was oil. Crude prices jumped after President Trump rejected Iran's proposal for a short-term reopening of the Strait of Hormuz. Brent Crude rose about 2% to 2.5%, moving toward $107 a barrel, while WTI climbed toward $94 to $95. Higher energy costs revived Inflation concerns, and energy was the only S&P 500 sector to finish higher.
The second was a sharp rise in Treasury yields. The 10-year yield climbed to about 5.26% to 5.27%, its highest level since 2007, and the 30-year yield also reached multi-year highs. Markets priced roughly a 70% chance of a Federal Reserve rate hike at the late-October meeting, up from the prior week. Higher yields reduce the present value of future earnings, which hits growth and technology stocks hardest.
The third was weakness in AI and semiconductor names. Memory-related stocks and chipmakers, including Micron (NASDAQ:MU) and AMD (NASDAQ:AMD), fell several percent, and some reports also cited AI-safety headlines involving OpenAI. Nvidia (NASDAQ:NVDA) was a notable exception after it expanded its share buyback program by $150 billion.
Breadth by the Numbers
|
Metric |
Gainers (5% or more) |
Decliners (5% or more) |
|
Number of stocks |
27 |
99 |
|
Median one-day move |
+7.5% |
-6.3% |
|
Moves between 5% and 10% |
22 |
92 |
|
Moves above 10% |
5 |
7 |
|
Higher over the past week |
19 |
11 |
|
Higher over the past month |
12 |
15 |
|
Median one-month return |
-1.2% |
-14.9% |
The headline ratio is stark. For every large-cap stock that gained 5% or more, nearly four fell by at least that much. The median decliner fell 6.3%, and 71 of the 99 decliners lost between 5% and 7%. Only seven fell by more than 10%, and two of those, a thinly traded PureCycle unit series (NASDAQ:PCTTU) and Digital currency X Technology (NASDAQ:DCX), show figures that look unreliable. Excluding those two, the average decliner fell 6.8%.
This pattern points to broad, orderly de-risking rather than panic. Selling touched a wide range of companies by a similar amount, which is typical of a macro-driven session.
The gainers list tells a different story. The median gainer rose 7.5%, but the group was lifted by a few outsized moves. Kodiak Sciences (NASDAQ:KOD) soared 182.8% after positive Phase 3 data in wet age-related macular degeneration, skewing the group average to 14.8%. Excluding Kodiak, the average gain was 8.3%.
Where the Selling Concentrated
The decliners were spread almost evenly across five broad groups of roughly 20 stocks each.
Gold and silver miners made up one of the largest clusters, with 20 names falling 5% or more, led by Gold Fields (NYSE:GFI) at 12.8%. That decline came even as geopolitical tension rose. The pattern is consistent with pressure from higher yields and rising rate-hike expectations, which tend to weigh on non-yielding Assets such as gold and, in turn, on Mining equities.
Software, Fintech and internet stocks formed another cluster of 20, led by a 17.2% drop in MongoDB (NASDAQ:MDB). These are classic long-duration growth stocks, and their weakness fits the yield-driven explanation closely. Nineteen of the 20 are also lower over the past month.
AI infrastructure, chip and crypto-linked names accounted for 19 decliners, including Modine Manufacturing (NYSE:MOD), VNET Group (NASDAQ:VNET), Bloom Energy (NYSE:BE), Arm Holdings (NASDAQ:ARM) and Qualcomm (NASDAQ:QCOM). This group stands out because 11 of the 19 remain higher over the past month, suggesting profit taking in names that had run up strongly.
Power, energy transition and industrial stocks added 20 more, from utilities and nuclear developers such as NuScale Power (NYSE:SMR) to geothermal developer Fervo Energy (NASDAQ:FRVO) and hydrogen, battery and electrical equipment makers. Many of these companies are capital intensive and rely on financing to grow, which makes them sensitive to higher borrowing costs. A final group of 20 covered aerospace, healthcare, consumer and services names, including Boeing (NYSE:BA), Aurora Innovation (NASDAQ:AUR) and Ocular Therapeutix (NASDAQ:OCUL).
Where Buyers Showed Up
Healthcare dominated the gainers, supplying 17 of the 27 Large-Cap Stocks that rose 5% or more. Most of these moves were company specific rather than part of a sector rotation. Outside healthcare, gains came from a scattered mix of names such as AMC Entertainment (NYSE:AMC), Victoria's Secret (NYSE:VSXY), Howard Hughes Holdings (NYSE:HHH) and Corporacion America Airports (NYSE:CAAP).
Notably, no energy stocks appear on the list of large gainers, even though energy was the only S&P 500 sector to finish higher. That suggests the sector's advance came from steady gains in large producers rather than outsized moves in individual names.
What the Trend Data Adds
The one-week and one-month figures add important context. Among the 99 decliners, 88 are lower over the past week and 84 are lower over the past month, with a median monthly decline of 14.9%. Monday's selling therefore extended an existing downtrend for most of these stocks rather than interrupting a rally.
The gainers look weaker on the same measure. While 19 of the 27 are higher over the week, only 12 are higher over the month, and the median monthly return for the group is slightly negative at 1.2%. Many of Monday's large gains appear to be rebounds within weaker trends rather than breakouts, which limits how much comfort investors can take from the advancing side.
What Investors Are Watching
Attention now turns to two major data releases this week. The PCE inflation report is due on Wednesday, followed by the September jobs report on Friday. Both will shape expectations for whether inflation and interest rates remain elevated, and whether the Federal Reserve moves toward a hike in late October.
Markets also remain sensitive to any further developments involving Iran and oil supplies through the Strait of Hormuz. If yields and oil prices stay high, the breadth pattern seen on Monday, with broad pressure on growth, mining and power infrastructure stocks, could persist. A cooler inflation reading, by contrast, could give oversold areas room to recover.
Disclaimer: This article is for general information only and does not constitute Investment advice. Readers should do their own research before investing.


 Nov 20, 2026





 Please wait processing your request...