
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Home Depot posted adjusted Earnings Per Share of 4.92 dollars, ahead of the 4.73 dollars analysts had projected.
- Revenue for the quarter reached 47.86 billion dollars, surpassing the 47.27 billion dollar consensus estimate.
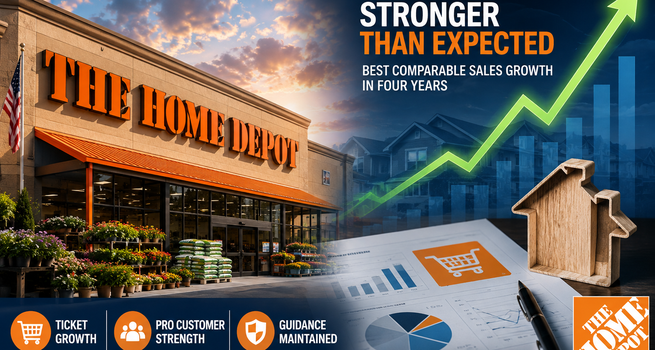
- Comparable sales climbed 1.7 percent, marking the strongest print since the third quarter of fiscal 2022.
- The company reaffirmed its full year guidance rather than raising it, citing persistent macroeconomic uncertainty.
- A Leadership transition is underway, with the finance chief assuming an expanded operational mandate.
Home Depot (NYSE:HD) delivered second quarter fiscal 2026 results that cleared Wall Street's bar on both earnings and revenue, reinforcing the retailer's narrative of steady execution inside a housing market that has yet to thaw. The results signal that the world's largest home improvement retailer continues extracting growth through Market Share gains even as broader Demand conditions remain constrained.
Earnings and Revenue Performance
Home Depot reported net sales of 47.9 billion dollars for the quarter, an increase of 5.7 percent from the prior year period. Net earnings came in at 4.8 billion dollars, or 4.79 dollars per diluted share, compared with 4.6 billion dollars, or 4.58 dollars per diluted share, a year earlier. On an adjusted basis, Diluted Earnings per Share reached 4.92 dollars, up from 4.68 dollars in the same quarter of fiscal 2025.
Both headline metrics outpaced analyst consensus expectations, with adjusted earnings per share exceeding estimates by roughly four percent and revenue beating projections by a similar margin. The scale of the beat suggests underlying demand resilience that had not been fully priced into analyst models heading into the print.
Comparable Sales Signal Renewed Momentum
Comparable sales rose 1.7 percent company wide, well ahead of the 0.9 percent gain analysts had anticipated. Comparable sales in the United States increased 1.3 percent. Management characterized this as the strongest comparable sales performance in roughly four years, a data point that carries weight given how persistently elevated Mortgage rates and subdued housing turnover have weighed on discretionary home improvement spending.
The gain came despite a decline in comparable customer transactions, which fell 1.0 percent, offset by a 2.8 percent increase in average ticket size. This composition, fewer transactions but higher spend per visit, points to customers engaging selectively in smaller scale projects rather than broad based discretionary spending, a distinction management drew explicitly when describing current housing conditions as frozen.
Pro and Consumer Segments Both Contribute to Share Gains
Executives attributed the quarter's strength to broad engagement across both professional contractor and do it yourself customer segments, framing the results as evidence of market share capture rather than category expansion. The professional customer base has historically shown greater insulation from macroeconomic Volatility relative to discretionary consumer spending, a dynamic that continues to support Home Depot's Diversification strategy following its SRS Distribution acquisition.
Management indicated that consumers retain the financial capacity to spend but remain hesitant to commit to larger scale renovation projects, citing concerns over inflation, fuel costs, and general economic uncertainty. This hesitancy appears concentrated at the higher end of project scale, with smaller scale spending proving comparatively resilient.
Guidance Reaffirmed Amid Tariff Considerations
Home Depot reaffirmed its fiscal 2026 guidance rather than raising it despite the quarterly beat, a decision management attributed to continued uncertainty in the operating environment. The guidance framework anticipates total sales growth of approximately 2.5 percent to 4.5 percent, comparable sales growth of approximately flat to 2.0 percent, and operating Margin of approximately 12.4 percent to 12.6 percent.
Notably, the guidance incorporates tariff refunds under the International Emergency Economic Powers Act, which the company expects will partially offset unplanned fuel, energy, and other product input costs over the remainder of the fiscal year. Management noted that these refunds support the company's ability to maintain pricing value for customers despite ongoing cost pressures elsewhere in the business, an important consideration for margin sustainability analysis.
Adjusted diluted earnings per share for the full fiscal year are projected to grow approximately flat to 4.0 percent from the 14.69 dollar base recorded in fiscal 2025.
Leadership Transition Adds Governance Dimension
The quarter's results arrive alongside a notable leadership development. Home Depot disclosed that its chief executive is taking a temporary medical leave of absence for several months. In the interim, operational oversight of United States stores has shifted to the senior executive vice president of stores and operations, while the chief financial officer has assumed an expanded mandate covering financial management and the professional Business segment.
This transition introduces a governance variable worth monitoring, though the immediate market reaction and the quarter's operational beat suggest limited disruption to near term execution. The concentration of expanded authority within existing senior leadership, rather than external succession uncertainty, may help explain the market's measured response.
Balance Sheet and Capital Allocation
Total Assets stood at 109.4 billion dollars as of the end of the second quarter, up from 100.0 billion dollars a year earlier, reflecting both organic growth and Acquisition related Balance Sheet expansion. Cash and cash equivalents totaled 2.1 billion dollars. The company generated 11.4 billion dollars in net cash from Operating Activities over the first six months of the fiscal year, compared with 9.0 billion dollars in the prior year period, an improvement that reflects favorable Working Capital dynamics.
Home Depot also disclosed capital expenditures of approximately 1.7 billion dollars for the first half of the fiscal year, alongside 1.3 billion dollars in payments for acquired businesses, underscoring continued Investment in both organic capacity and inorganic growth channels.
Risk Considerations
Several factors Warrant continued monitoring. Housing market conditions remain a structural headwind, with elevated mortgage rates continuing to suppress the large scale renovation projects that typically accompany home purchases and turnover. Tariff policy remains a variable input, with the current guidance dependent on the continuation of anticipated refund mechanisms. The temporary leadership transition, while apparently well managed operationally, introduces a governance Factor that investors may weigh over the coming months. Inflation and fuel cost pressures, cited directly by management as sources of customer hesitancy, could continue to constrain the pace of large project spending even as smaller scale engagement remains steady.
Outlook
Taken together, the quarter reinforces a pattern that has now persisted across several reporting periods: Home Depot's growth is increasingly a function of execution and share capture rather than a recovering housing cycle. Management's decision to reaffirm rather than raise guidance, despite a clear beat on both revenue and earnings, reflects a deliberate calibration between near term momentum and a macroeconomic backdrop that remains unresolved on mortgage rates, tariff policy, and consumer willingness to fund larger projects.
The composition of this quarter's comparable sales gain, driven by ticket size rather than transaction volume, will be worth tracking into the second half. A sustained shift toward larger project spending would signal genuine demand recovery; a continuation of the current pattern would suggest the company is simply becoming more efficient at monetizing a still cautious customer base. The leadership transition adds a governance variable to watch, though the redistribution of responsibilities among established executives, rather than an external search, points to continuity as the base case. For now, the balance of evidence favors Home Depot's operational positioning over the cyclical environment it operates within.

 Nov 16, 2026
 Please wait processing your request...