
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed mostly lower on Thursday, with the S&P 500 falling 1.2% and Nasdaq dropping 2.9%, while the Dow finished flat as disappointing Earnings and concerns over debt-funded AI spending weighed on technology shares. Meta sank 7%, while Alphabet, Microsoft and Amazon declined ahead of earnings. Lam Research plunged 11.8% on a weak outlook, semiconductor stocks recorded steep losses, and Tesla fell 3.1% after scaling back spending plans.
Market Movers
Among the top-performing stocks of the session Tantech Holdings Ltd. surged 181.84%, while Exascale Labs Holdings Inc. rallied 73.16%. On the losing side, Avalo Therapeutics, Inc. fell 39.23%, while NVE Corporation. declined 33.68%, making them the weakest performers during the trading day.
Commodities Update
Crude oil rose above USD 100 per barrel on Friday, nearing a five-week high, while Brent surpassed USD 114 as Houthi attacks on Saudi infrastructure and reports of potential renewed US-Israeli strikes on Iran heightened Middle East Supply concerns. Ukraine’s intensified attacks on Russian refineries added to supply risks, although Persian Gulf crude exports recovered close to prewar levels despite continued threats to shipping through the Strait of Hormuz.
Gold fell toward USD 4,000 an ounce on Friday, nearing a three-month low, while silver declined to around USD 54, its lowest since November 2025, as a technology-led Equity selloff prompted investors to liquidate precious metals to cover losses. Meta’s planned Capital Expenditure increase fuelled concerns over debt-funded AI investment, while rising oil prices reinforced Inflation worries and expectations of prolonged elevated interest rates. However, doubts over AI Investment sustainability tempered expectations of further Federal Reserve rate hikes, offering potential support for both metals.
Macro Updates
Dollar Near Three-Week Low as Treasury Yields Decline
The US dollar index hovered near 101.6 on Friday as a technology-led selloff drove investors toward government bonds, pushing Treasury yields lower. Concerns over AI investment sustainability tempered Fed tightening expectations, with markets pricing in a 91% probability of unchanged rates next week and an 80% chance of a December hike. The dollar weakened notably against the yen amid stronger safe-haven demand.
Kansas City Manufacturing Growth Eases, Outlook Strengthens
The Kansas City Fed’s Manufacturing Production Index declined to 16 in October 2026 from 20 in September, reflecting slower growth across durable and nondurable goods. Order backlogs and new export orders contracted, while employment, supplier delivery times and materials inventories increased. Raw material price pressures accelerated as finished goods price growth eased, while expectations for future activity reached their strongest level since July 2022.
Bonds Commentary
The US 10-year Treasury Yield held near 4.97% on Friday after dropping more than 10 basis points to a one-month low as a technology-led selloff and escalating Middle East tensions boosted Demand for government bonds. Concerns over AI investment sustainability also tempered Fed tightening expectations, with markets pricing in a 91% probability of unchanged rates next week and an 80% likelihood of a December hike.
Futures Update
US stock futures were little changed on Friday after concerns over AI investment sustainability triggered a technology-led selloff. The Nasdaq fell 2.6% and S&P 500 dropped 1.21% on Thursday, while the Dow edged up 0.02%. Meta’s plans to raise capital spending fuelled worries about debt-funded AI expansion, weighing on semiconductor and technology stocks, while escalating Middle East tensions further encouraged a shift toward bonds.
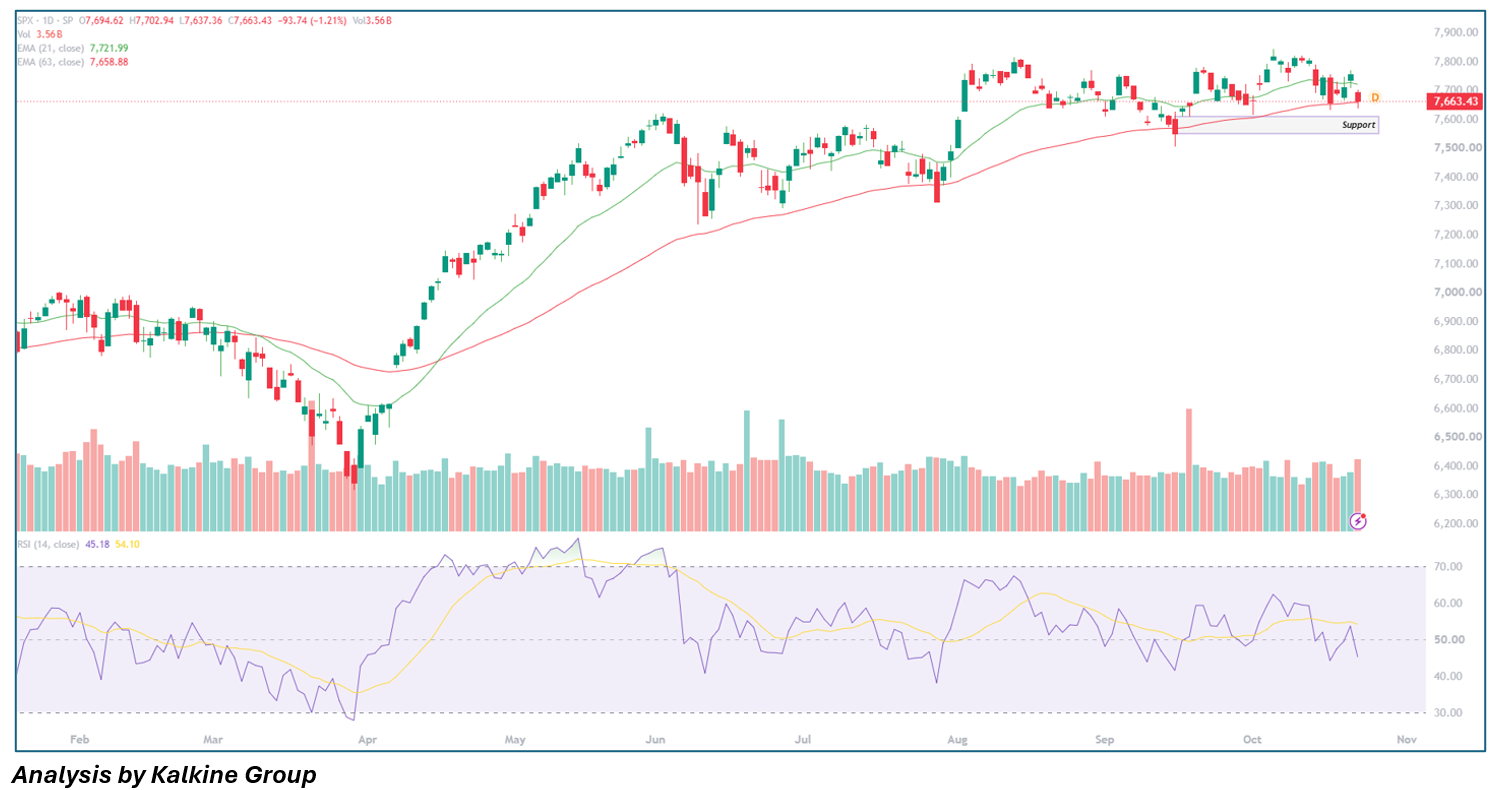
Stocks reversed sharply lower on Thursday after several sessions of gains, with the tech-heavy Nasdaq leading the decline to its weakest close in more than a month. Both the Nasdaq and the S&P 500 finished close to their session lows. The S&P 500 settled at 7,663.43, a loss of 93.74 points (-1.21%), having traded between 7,637.36 and 7,702.94 on Volume of 3.56B. The index dropped below its 21-day EMA at 7,721.99 and closed essentially on its 63-day EMA at 7,658.88, a level that has served as dynamic support throughout the recent consolidation. The red candle formed on rising volume, which points to genuine selling pressure rather than a gradual slide. RSI (14) declined to 45.18, under both its signal line at 54.10 and the neutral 50 level, indicating that momentum has weakened without yet reaching oversold territory. The next major level is the marked support zone of roughly 7,520 to 7,620. A close beneath the 63-day EMA would bring that zone into focus, whereas a bounce from current levels would keep the index within a range of about 7,640 to 7,800.

 Oct 28, 2026
 Please wait processing your request...