
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed lower on Wednesday as elevated yields and tight Credit conditions weighed on Earnings expectations. The S&P 500 and Nasdaq 100 each fell 0.2%, while the Dow lost 341 points. Hawkish FOMC minutes pressured AI chipmakers and hyperscalers, with Nvidia, AMD, Meta and Oracle declining despite news of SpaceX’s planned USD 40 billion borrowing to purchase Nvidia chips. SpaceX and Tesla also fell, while pharmaceutical and consumer staples stocks advanced.
Market Movers
Among the top-performing stocks of the session China SXT Pharmaceuticals, Inc. surged 126.40%, while Pinnacle Food Group Limited. rallied 116.67%. On the losing side, WISeSat.Space Holdings Corp. fell 24.61%, while Cel-Sci Corporation. declined 22.26%, making them the weakest performers during the trading day.
Commodities Update
Crude oil rose above USD 92.6 per barrel and Brent topped USD 105 on Thursday, reaching nearly one-month highs as Supply concerns intensified. Reports of potential US strikes against Iran, President Trump’s rejection of a deal, and escalating attacks on Gulf shipping and Saudi Arabia heightened geopolitical risks. Prices were also supported by Tropical Storm Isaias, which prompted offshore evacuations and production cuts, shutting in around 25.1% of US Gulf of Mexico oil output and 16.4% of Natural Gas production.
Gold traded near USD 4,100 an ounce and silver slipped below USD 60 on Thursday, both hovering near their lowest levels since early August as hawkish FOMC minutes and elevated oil prices weighed on sentiment. Most Fed policymakers favoured another rate hike before year-end, with markets pricing in around a 78% probability of a December increase. Meanwhile, reports of potential US strikes against Iran and continued risks to Strait of Hormuz shipping supported oil prices, reinforcing Inflation concerns despite Middle Eastern oil flows recovering to prewar levels.
Macro Updates
The dollar index held above 102 on Thursday, near its strongest level since April 2025, supported by hawkish FOMC minutes and safe-haven Demand amid US–Iran tensions. Markets expect rates to remain unchanged this month but price in a 78% chance of a December hike, while elevated oil prices reinforce inflation concerns. Investors await weekly US jobless claims for further insight into labour market conditions.
Bonds Commentary
The US 10-year Treasury Yield rose to 5.35% on Thursday, its highest since 2002, as rising oil prices fuelled inflation concerns and expectations of further Fed tightening. September meeting minutes and Governor Waller’s comments supported the prospect of additional hikes, with markets pricing an 81% chance of an October pause and a 71% probability of a 25-basis-point December increase. The upcoming 30-year Treasury auction will test demand for longer-dated debt.
Futures Update
US Equity futures fell on Thursday as multi-decade-high Treasury yields and surging oil prices intensified concerns over borrowing costs, inflation and further Fed rate hikes. S&P 500 futures dropped 0.6%, while Nasdaq 100 and Dow futures declined around 1%. AI infrastructure stocks led losses, with Intel, Lam Research, Marvell and Micron falling about 2% each, while Broadcom slipped 1.5% after issuing USD 60 billion in Debt to support Anthropic’s expansion.
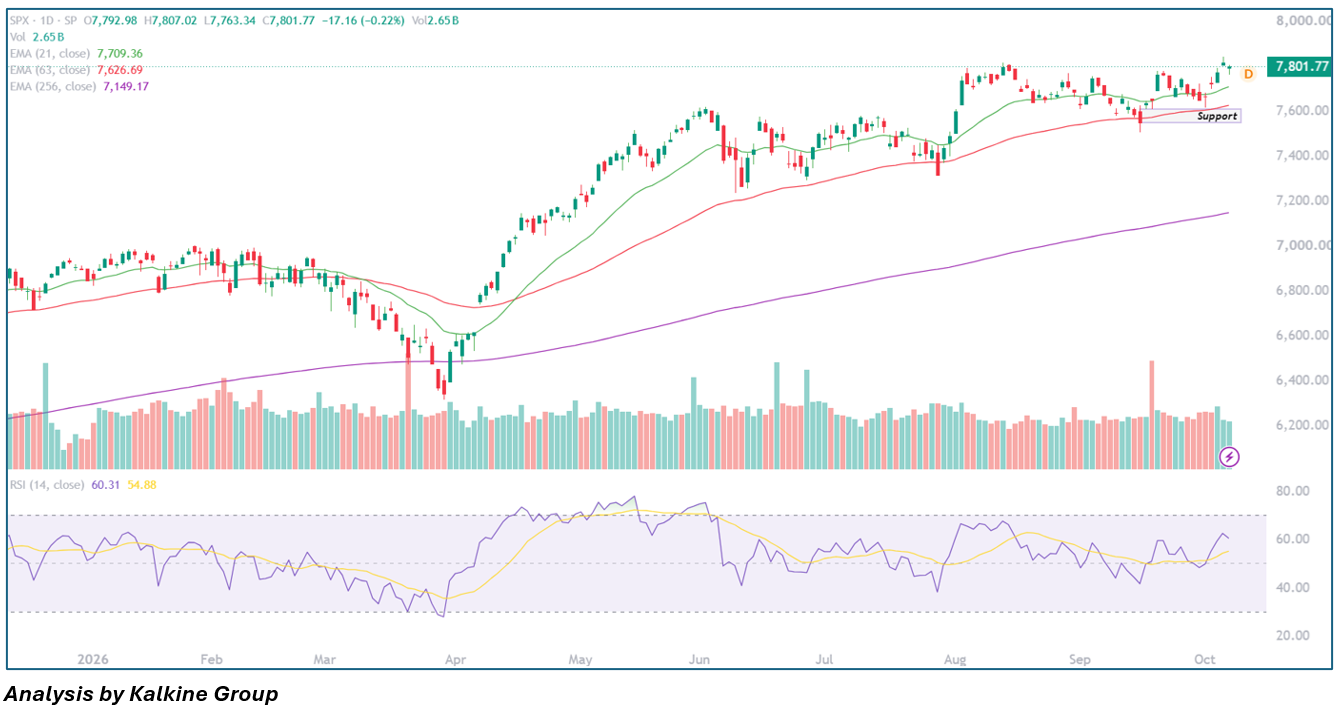
U.S. stocks climbed for several sessions in a row, then slipped at the open on Wednesday before recovering a good part of the loss during the day. The major averages rebounded well off their session lows but still finished slightly lower. The S&P 500 (SPX) closed down 0.22% at 7,801.77 after being rejected near 7,830, and the short-term read leans bearish. The index opened at 7,792.98 and traded between 7,763.34 and 7,807.02. It could not hold the prior session's push above 7,800, which left a long upper wick on the chart. The longer-term trend is still up, with the 21-day EMA (7,709.36), 63-day EMA (7,626.69) and 256-day EMA (7,149.17) all rising and sitting below price. Even so, the index is about 1.2% above its 21-day EMA and has made little progress since early August.

 Nov 03, 2026





 Please wait processing your request...