
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed mostly higher on Thursday as easing Treasury yields helped markets recover earlier losses. The S&P 500 gained 0.2%, the Nasdaq rose 0.3%, and the Dow finished near flat. Fed Vice Chair Philip Jefferson’s comments favouring more time to assess further rate hikes supported bonds and rate-sensitive stocks. Chipmakers advanced, with Nvidia rising 1.1%, AMD gaining 0.6%, and Micron climbing 3% following strong quarterly results and an upbeat forecast.
Market Movers
Among the top-performing stocks of the session Sono Group N.V. surged 97.32%, while Nexalin Technology, Inc. rallied 76.40%. On the losing side, Corteva, Inc. fell 83.81%, while VerifyMe, Inc. declined 38.31%, making them the weakest performers during the trading day.
Commodities Update
Crude oil fell nearly 4% to around USD 89 a barrel, while Brent declined more than 3% to approximately USD 99 on Friday, as European governments considered releasing strategic reserves to ease fuel costs and diesel shortages amid US pressure. Middle Eastern crude flows nearing pre-war levels also eased Supply concerns, although uncertainty over US–Iran negotiations to fully reopen the Strait of Hormuz, reported tanker attacks and Ukrainian strikes on Russian refineries continued to pose risks.
Gold held below USD 4,200 an ounce on Friday, heading for a second consecutive weekly decline, while silver steadied near USD 60.5 and was set for a weekly loss of approximately 5%. Both metals faced pressure from a stronger dollar, elevated Treasury yields and Inflation concerns linked to higher oil prices amid potential US–Iran escalation. Investors awaited the September US jobs report for clues on Federal Reserve policy, while Minneapolis Fed President Neel Kashkari stressed that further rate increases could be needed to bring inflation under control.
Macro Updates
US Job Growth Expected to Moderate as Labor Market Remains Stable
The US economy is forecast to have added 90,000 jobs in September, down from 162,000 in August, with private employers contributing 85,000. Slower hiring in leisure, hospitality and local government education is expected to be partly offset by strong Manufacturing and construction gains, supported by AI data-center investment. Unemployment is projected to remain at 4.1%, while average hourly Earnings are expected to rise 0.3% monthly and 3.2% annually, suggesting broadly stable labor conditions.
Dollar Heads for Third Weekly Gain as Yields and Geopolitical Risks Rise
The dollar index rose above 102 on Friday, heading for a third consecutive weekly gain as US economic resilience, elevated Treasury yields and Middle East tensions supported demand. Investors awaited September jobs data for clues on Fed policy, while hawkish remarks from Neel Kashkari and oil-driven inflation concerns reinforced expectations of further monetary tightening.
Bonds Commentary
The US 10-year Treasury Yield held near 5.26% on Friday, easing from multi-decade highs as concerns over France’s fiscal and political outlook supported safe-haven demand. Yields remained elevated amid expectations of further Fed tightening, resilient US economic activity and fiscal concerns. Investors awaited September jobs data, while higher oil prices and potential US–Iran escalation added to inflation risks.
Futures Update
US stock futures were little changed on Friday ahead of the September jobs report, with traders pricing in roughly a 75% chance of unchanged Fed rates this month. Investors also monitored potential US military deployments to the Middle East and reports of an Anthropic IPO as early as mid-November. On Thursday, the S&P 500 gained 0.19%, while the Dow and Nasdaq each rose 0.04% as Treasury yields eased from multi-decade highs
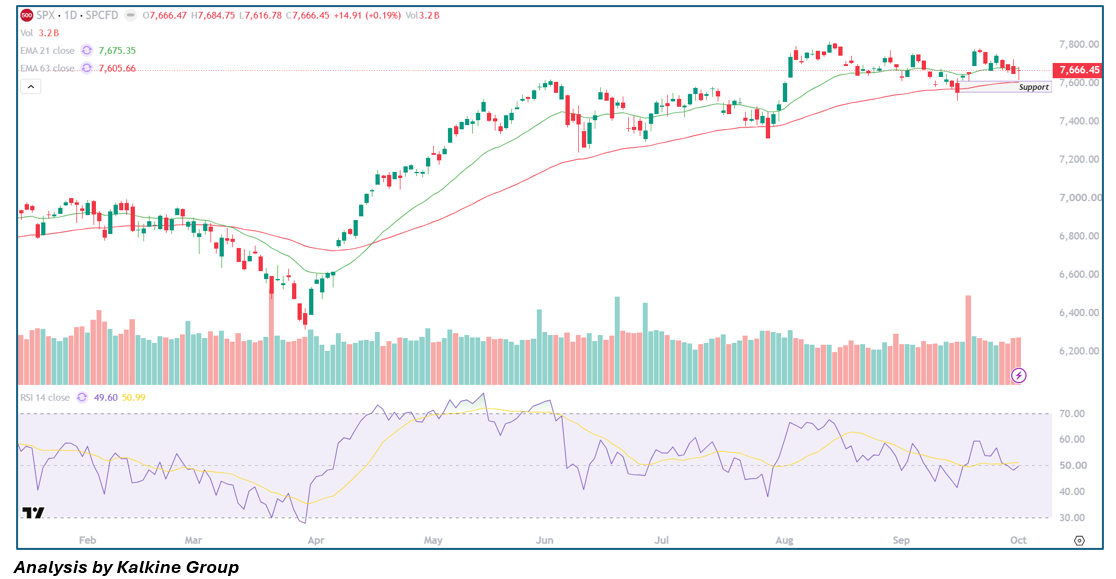
The S&P 500 ended Thursday almost flat at 7,666.45 (+0.19%), forming a near-doji after dipping to 7,616.78 and recovering, which signals indecision. Price sits just below the 21 EMA (7,675) and above the 63 EMA (7,606) and support zone (7,605 to 7,615), with neutral RSI (49.6) and light volume. The key pivot is 7,675 to 7,685: a hold above targets 7,720 to 7,750, while a break below 7,617 (and especially a close under 7,600) risks a slide toward 7,500. The base case is range-bound trade below the August high. This is a technical read, not financial advice.

 Nov 03, 2026





 Please wait processing your request...