
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed lower on Tuesday, with the S&P 500 near flat, the Dow down 180 points and the Nasdaq falling 0.3%. Semiconductor shares declined amid advances by China’s CXMT and concerns over returns on AI spending, led by Applied Materials’ 7.2% drop and Micron’s 4.6% fall. Johnson & Johnson lost 5.6% on weaker sales, while major banks declined as investors weighed Earnings strength against trading weakness and rising costs.
Market Movers
Among the top-performing stocks of the session JBDI Holdings Limited. surged 243.00%, while Alaunos Therapeutics, Inc. rallied 188.57%. On the losing side, WF Holding Limited. fell 87.73%, while Bradbury Capital Inc. declined 40.20%, making them the weakest performers during the trading day.
Commodities Update
Crude oil traded below USD 95 per barrel and Brent hovered around USD 106 on Wednesday as improving Supply flows competed with escalating Middle East tensions. US-assisted shipments of over 19 million barrels through the Strait of Hormuz and a roughly one-third increase in Saudi Arabia’s September output eased supply concerns. However, Houthi attacks on Saudi locations, including an Aramco office complex, and Iranian strikes on tankers heightened uncertainty over Gulf energy shipments.
Gold traded near USD 4,150 an ounce and silver around USD 59 on Wednesday, following two sessions of losses, as investors awaited US Inflation data for clues on Federal Reserve policy. Markets priced in a 77% chance of unchanged rates this month and an 88% probability of a December hike, while New York Fed President John Williams suggested one further increase this year could suffice. Escalating Middle East hostilities heightened energy supply concerns, while the IMF warned that a potential slowdown in AI investment, rising Debt and prolonged conflict could threaten global growth and financial stability.
Macro Updates
US Inflation Accelerates as Energy Prices Surge
US consumer prices rose 0.6% month-on-month in September 2026, up from 0.4% in August and marking the largest increase since April, driven by a 5.2% rise in energy prices. Gasoline prices jumped 9.1%, accounting for more than half of the overall increase, while shelter costs rose 0.4% and food prices remained unchanged. Core CPI increased 0.3% monthly, exceeding the expected 0.2%, while annual Core Inflation climbed to 2.6% from 2.4%, slightly above the 2.5% forecast, signalling renewed underlying price pressures.
US Mortgage Applications Fall as Rates Reach 7.5%
US mortgage applications declined 2.7% in the week ended October 9, 2026, marking a sixth consecutive weekly fall and reaching their lowest level since January 2025. The average 30-year fixed mortgage rate rose one basis point to 7.5%, its eighth straight weekly increase and a near-three-year high. Elevated Treasury yields and expectations of prolonged restrictive Federal Reserve policy continued to raise borrowing costs, weighing on both refinancing and home purchase demand.
Bonds Commentary
The 10-year US Treasury Yield held near 5.21% on Wednesday as investors awaited September inflation data and further Fed commentary. John Williams suggested one more rate hike this year, while Christopher Waller described inflation expectations as well anchored. Markets priced in a 77% chance of unchanged rates this month and an 88% probability of a December hike, although easing Global Bond selling and safe-haven Demand amid Equity Volatility supported Treasury prices.
Futures Update
US stock futures were mixed on Wednesday, with S&P 500 and Dow contracts edging higher while Nasdaq 100 futures slipped ahead of inflation data and major earnings. Morgan Stanley and BlackRock gained on strong trading Revenue and asset inflows, while Micron and Marvell fell over 2% amid AI infrastructure supply constraints and rising Chinese competition. Expectations of elevated underlying inflation reinforced concerns about further Federal Reserve rate hikes this year.
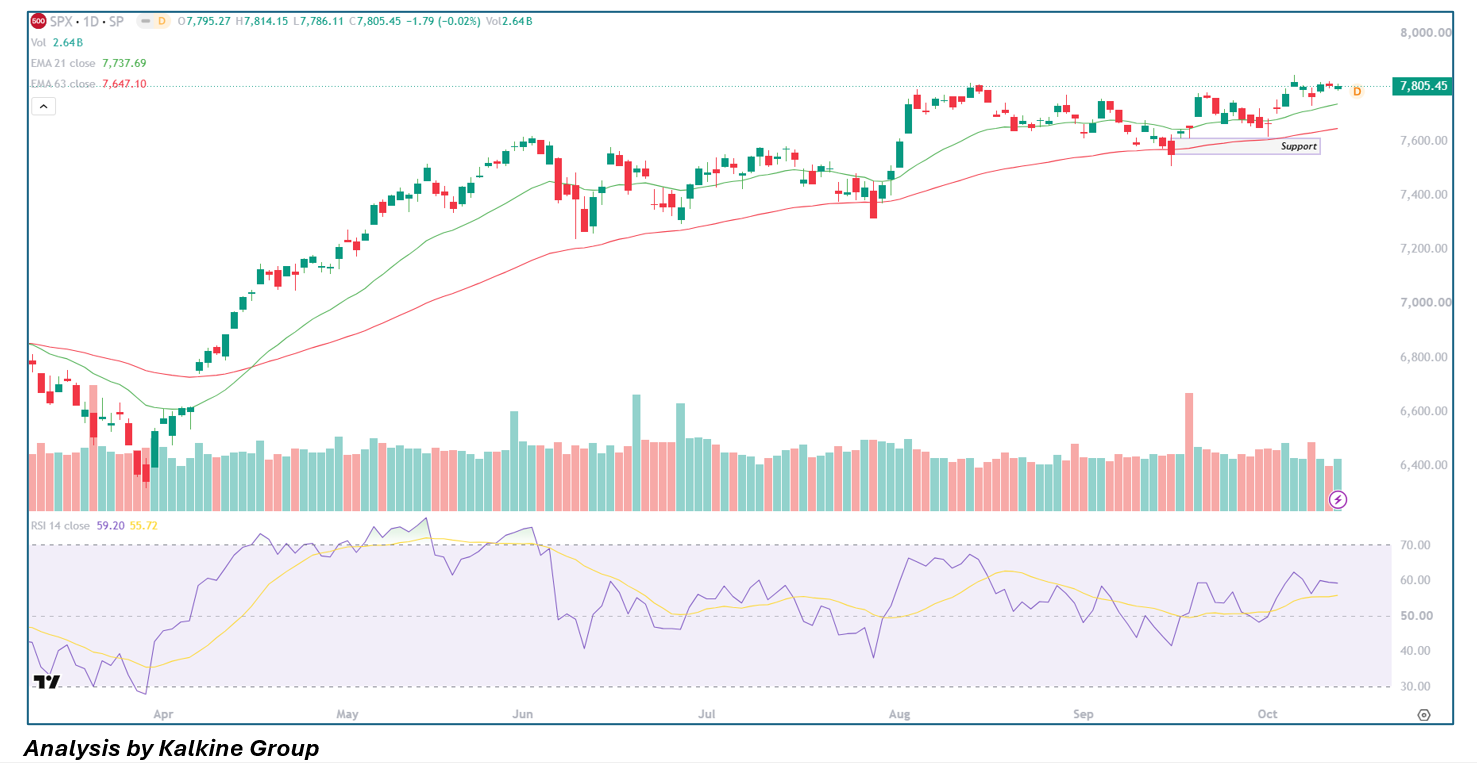
Stocks lacked direction throughout Tuesday’s session, continuing the subdued trading from the day before. The major averages moved back and forth around the unchanged line before settling modestly lower. The S&P 500 is moving in a tight consolidation range. Its latest daily candle is a small-bodied, doji-like bar (open 7,795, high 7,814, low 7,786, close 7,805, down 0.02%), which points to indecision just under the recent swing high near 7,830-7,840. The short-term bias is neutral to mildly bullish. Price remains above both the 21-EMA (7,738) and the 63-EMA (7,647), and both averages are still rising. RSI is around 59, above its signal line at 55.7 and short of overbought territory. A sustained push above 7,814, followed by a move through 7,840, could open the way to the 7,900-8,000 zone. A drop below 7,786 could trigger a pullback toward the 21-EMA near 7,738, with the 7,560-7,600 support zone as the stronger floor beneath that. Volume is light at 2.64B, so choppy, range-bound trading is likely until a breakout on heavier volume confirms the next direction.


 Nov 02, 2026



 Please wait processing your request...