
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks ended mixed on Thursday, with the S&P 500 falling 0.5% and the Nasdaq declining 1.4%, while the Dow gained 52 points. A report placing OpenAI’s annualised Revenue at USD 50 billion, below earlier estimates of USD 70 billion, renewed concerns over AI profitability and infrastructure spending. Nvidia, Broadcom and Micron fell sharply, alongside Microsoft, Alphabet and Oracle. Meanwhile, oil rebounded as attacks on tankers in the Strait of Hormuz and hurricane risks to Gulf of Mexico production heightened Supply concerns.
Market Movers
Among the top-performing stocks of the session Fly-E Group, Inc. surged 82.68%, while Pacira BioSciences, Inc. rallied 44.40%. On the losing side, Bradbury Capital Inc. fell 31.82%, while Apimeds Pharmaceuticals US, Inc. declined 21.84%, making them the weakest performers during the trading day.
Commodities Update
Crude oil fell below USD 91 a barrel and Brent eased to USD 103 on Friday as signs of progress in US–Iran talks reduced concerns over Middle East supply disruptions. President Trump’s pledge to refrain from attacking Iran ahead of the midterm elections, discussions over reopening the Strait of Hormuz and China’s planned resumption of refined fuel exports added downward pressure. However, persistent Gulf shipping threats and hurricane-related production shutdowns of approximately 1.3 million barrels per day in the Gulf of Mexico limited losses. For the week, crude prices were little changed, while Brent gained 2%.
Gold rose more than 1% to around USD 4,180 an ounce on Friday, reaching a one-week high, while silver gained over 2% to approximately USD 60.5, recovering from a two-month low. A softer US dollar and easing oil prices supported both metals after President Trump ruled out attacks on Iran before November’s midterm elections amid ongoing diplomatic efforts. However, expectations of further Federal Reserve tightening tempered gains, with St. Louis Fed President Alberto Musalem suggesting additional hikes may be needed to curb inflation. Markets priced in less than a 20% chance of an October hike and over an 80% probability of at least one 25-basis-point increase by December.
Macro Updates
The US dollar index held near 102.1 on Friday, heading for a fourth consecutive weekly gain of approximately 0.2% and trading at its highest level since April 2025. Oil prices eased after President Trump pledged to avoid attacks on Iran until after the midterm elections, reducing energy supply concerns. However, persistent Inflation supported expectations of higher-for-longer US interest rates, with markets pricing an 81% chance of unchanged rates this month and a 69% probability of a 25-basis-point hike in December.
Bonds Commentary
The US 10-year Treasury Yield edged up to 5.26% on Friday after falling six basis points on Thursday from its highest level since 2002, but remained down around five basis points for the week. Easing oil prices reduced inflation concerns, although expectations of prolonged monetary tightening persisted, with markets pricing an 81% chance of unchanged Fed rates this month and a 69% probability of a 25-basis-point hike in December. Strong Demand at the week’s 10-year and 30-year Treasury auctions indicated continued appetite for longer-dated government debt.
Futures Update
US Equity futures advanced on Friday, with S&P 500 and Nasdaq 100 contracts rising 0.5% and 1%, respectively, as AI stocks rebounded and Treasury yields eased. Major chipmakers gained over 2%, while Amazon, Alphabet and Meta rose around 1%. Investors looked past concerns over OpenAI’s revenue outlook, with SoftBank’s pursuit of USD 100 billion for AI ventures supporting sentiment. President Trump’s pledge to avoid strikes on Iran before November’s midterm elections also eased oil prices and inflation expectations.
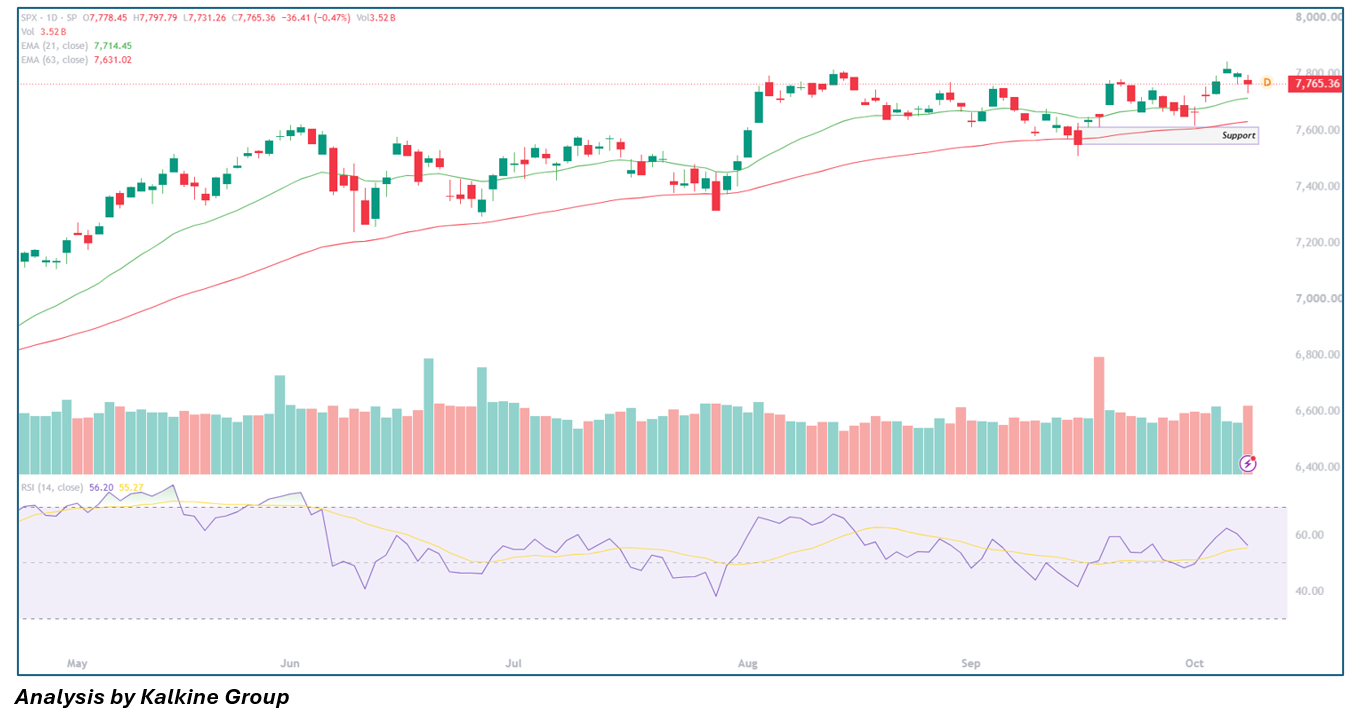
U.S. stocks ended mostly lower on Thursday, extending the modest losses from the previous session. The tech-heavy Nasdaq led the weakness, pulling back further from the record closing high it set on Tuesday. The S&P 500 (SPX) closed down 0.47% at 7,765.36, and the short-term view is bearish. The index opened at 7,778.45 and traded between 7,731.26 and 7,797.79, finishing in the lower half of that range on Volume of 3.52B. It was the second straight decline after the push toward 7,830 reversed, leaving a lower high and a rejection wick at the top of the range that has held since August. The 21-day EMA (7,714.45) and 63-day EMA (7,631.02) are both rising and sit below price, so the broader uptrend is intact. Even so, the index is only about 0.7% above the 21-day EMA, and today's low of 7,731 came close to testing it. RSI at 56.20 has rolled over from the low 60s and is approaching its 55.27 signal line, a sign of fading momentum. A break below today's low at 7,731 would bring the 21-day EMA near 7,714 into play, followed by the 63-day near 7,631, with the 7,550 to 7,600 support zone, which held in September, as the key area below.


 Nov 02, 2026




 Please wait processing your request...