
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks ended mixed on Monday, with the S&P 500 little changed, the Nasdaq down 0.4% and the Dow up 196 points as investors awaited Earnings and Inflation data. Tech weakness weighed on markets, with Micron falling 3.9% amid competition concerns and Nvidia losing 1.3%. Meta rose 3.4% following an AI model launch, while Salesforce gained 2.1% after an analyst upgrade. Energy stocks benefited from higher oil prices as attacks on Riyadh’s airport and continued strikes on Ukrainian energy infrastructure heightened Supply concerns, lifting Chevron 1.4%.
Market Movers
Among the top-performing stocks of the session Mobile-health Network Solutions. surged 257.65%, while Linkers Industries Limited. rallied 138.37%. On the losing side, Vivakor, Inc. fell 42.89%, while Contineum Therapeutics, Inc. declined 35.99%, making them the weakest performers during the trading day.
Commodities Update
Crude oil fell below USD 93 per barrel and Brent eased toward USD 105 on Tuesday, ending three-session winning streaks as Russia’s partial lifting of diesel export restrictions eased fuel supply concerns. However, geopolitical risks remained elevated amid US lawmakers’ objections to the Trump–Putin agreement, continued attacks on energy infrastructure in Russia and Ukraine, and pressure on Washington to support Saudi Arabia following Houthi attacks on Riyadh’s main airport.
Gold held below USD 4,200 an ounce and silver fell toward USD 60 on Tuesday as the US dollar reached an 18-month high ahead of Wednesday’s consumer inflation and Thursday’s producer inflation reports. Markets priced in an approximately 80% chance of unchanged Fed rates this month and an 88% probability of a December hike. Meanwhile, tensions involving Saudi Arabia and Houthi militants, alongside violations of the Russia–Ukraine energy ceasefire, kept oil prices elevated, reinforcing inflation concerns and expectations of further monetary tightening.
Macro Updates
US Small Business Optimism Falls as Hiring and Inflation Concerns Rise
The NFIB Small Business Optimism index declined to 97.9 in September 2026 from 98.7 in August, reaching a three-month low and broadly matching forecasts. Weaker expectations for business conditions and reduced enthusiasm for expansion drove the decline. Labour quality and availability remained the leading concern, cited by 26% of owners, while inflation rose to 20%, reflecting growing caution over costs, interest rates and hiring challenges.
Dollar Retreats from 18-Month High Ahead of US Inflation Data
The dollar index eased to 102.3 on Tuesday from 102.6 as oil prices and US Treasury yields declined ahead of key inflation reports, including Wednesday’s CPI release. Markets priced in a 19% chance of a 25-basis-point Fed rate hike this month and nearly 72% for December. The dollar weakened broadly, particularly against the yen, as expectations of further Bank of Japan rate hikes persisted despite softer-than-expected Japanese wholesale inflation.
Bonds Commentary
The US 10-year Treasury Yield fell 5 basis points to 5.19% on Tuesday, easing from recent 24-year highs as a global tech sell-off boosted Demand for safer Assets and lower oil prices supported bonds. Investors awaited Wednesday’s CPI report for clues on inflation and Fed policy, with markets pricing in a 19% chance of a 25-basis-point rate hike this month and nearly 72% for December.
Futures Update
US stock futures were mixed on Tuesday, with S&P 500 and Nasdaq 100 futures down 0.1% and 0.2%, respectively, while Dow futures rose 0.05%. Investors awaited earnings from major banks, Johnson & Johnson and UnitedHealth, alongside existing home sales data and Fed officials’ remarks ahead of Wednesday’s inflation report. On Monday, weakness in memory chip stocks pushed the S&P 500 and Nasdaq lower, while the Dow advanced 0.38%.
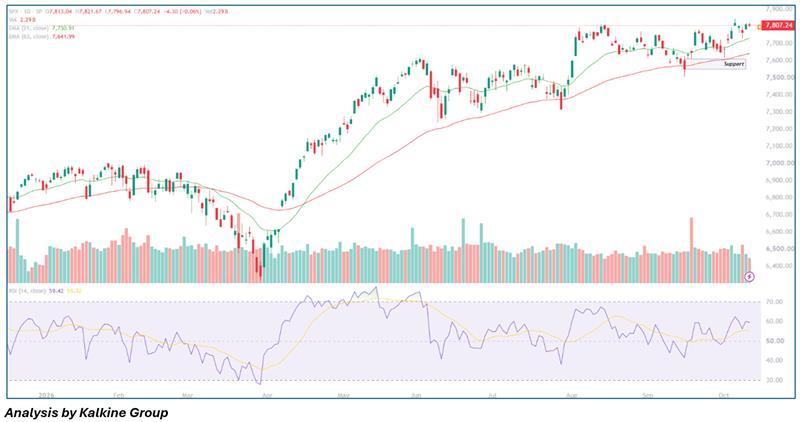
Stocks ended last week on a positive note but turned lackluster on Monday, with the major averages moving in opposite directions and finishing mixed. The S&P 500 closed nearly flat at 7,807 after a narrow session between 7,797 and 7,822, and its uptrend remains intact, with price holding above the rising 21 EMA (about 7,731) and 63 EMA (about 7,642) and RSI at a healthy 59. The bias is mildly bullish but likely choppy: a move above 7,822 on stronger Volume could target 7,850 to 7,880, while a drop below 7,795 may pull the index toward the 21 EMA near 7,730, which would more likely be a dip within the uptrend than a reversal. Volume has been fading near the highs, pointing to weak conviction, so range-bound trading between 7,795 and 7,822 is quite possible. This is a technical read of one chart and not financial advice.


 Nov 02, 2026




 Please wait processing your request...