
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks rose on Friday as weaker-than-expected Jobs Growth reduced bets on further Fed tightening, while lower oil prices supported bonds and equities. The S&P 500 gained 0.7%, the Dow added 250 points and the Nasdaq climbed 1% to a record 30,808. AI and technology stocks advanced, while Tesla jumped 4.6% following better-than-expected third-quarter sales. For the week, the S&P 500 rose 0.2% and the Nasdaq gained 1.3%, while the Dow fell 319 points.
Market Movers
Among the top-performing stocks of the session Alpha Modus Holdings, Inc. surged 198.29%, while Stablecoin Development Corporation. rallied 104.37%. On the losing side, SMX (Security Matters) Public Limited Company. fell 37.99%, while NorthStar Earth & Space Enterprises, Inc. declined 36.43%, making them the weakest performers during the trading day.
Commodities Update
Gold rose above USD 4,150 an ounce and silver exceeded USD 61 on Monday as weaker-than-expected US jobs growth and slowing wages reduced expectations of an immediate Federal Reserve rate hike. September payrolls increased by just 29,000, while Unemployment rose to 4.2% and annual wage growth slowed to 3.0%, lifting the probability of unchanged rates this month to nearly 80%. However, expectations of a December hike remained around 69%, and elevated Treasury yields continued to pressure precious metals, while escalating conflict in Yemen added geopolitical uncertainty.
Crude oil held below USD 91 a barrel, while Brent traded around USD 102.5 on Monday as recovering Strait of Hormuz flows, a G7 emergency stockpile release and deeper Saudi Aramco discounts eased Supply pressures. Aramco cut November Arab Light prices for Asian buyers to USD 5 below the regional benchmark, compared with October’s USD 2 discount, signalling stronger competition for market share. Geopolitical risks persisted, although Saudi Arabia’s East-West pipeline continued operating normally following reports of a fresh attack, while OPEC+ kept next month’s production quotas unchanged.
Macro Updates
Dollar Strengthens as European Political Uncertainty Weighs on Euro
The dollar index rose to around 102.5 on Monday, its highest level since April 2025, as political uncertainty in Spain and concerns over France’s instability and fiscal outlook weakened the euro. The greenback advanced despite weak US jobs data reducing expectations of an immediate Fed rate hike. September payrolls increased by just 29,000, unemployment rose to 4.2% and wage growth slowed to 3.0%, leaving markets pricing nearly an 80% chance of unchanged rates this month and a 69% probability of a December hike.
Bonds Commentary
US Treasury yields eased on Monday, with the 10-year yield around 5.25% and the 30-year near 5.6%, as weak jobs growth and slowing wages reduced expectations of an imminent Fed rate hike. Markets priced nearly an 80% chance of unchanged rates this month, although December hike expectations remained around 69%. Yields stayed near multi-decade highs amid concerns over energy-driven inflation, US fiscal risks and increasing Debt issuance linked to artificial intelligence.
Futures Update
US stock futures edged down less than 0.2% on Monday as Treasury yields at their highest levels in over two decades raised concerns about borrowing costs and Equity valuations. Weak jobs data reduced expectations of a Fed rate hike this month, offering some relief. Investors now await Monday’s ISM services report, Wednesday’s Fed September meeting minutes and Friday’s preliminary October consumer sentiment reading for further policy and economic signals.
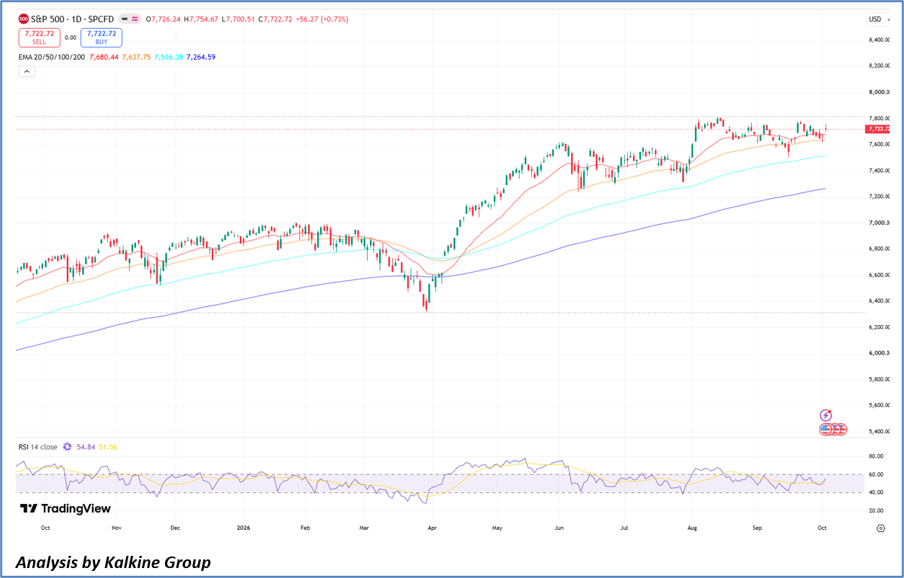
The S&P 500 closed at 7,722.72 (+0.73%), recovering from an intraday low of 7,700.51 and approaching the recent resistance zone around 7,750–7,800. Price remains above the 20 EMA (7,680.44), 50 EMA (7,637.75), 100 EMA (7,516.38) and 200 EMA (7,264.59), preserving the broader bullish trend, although the index continues to consolidate below its recent highs. The RSI is 54.84, indicating neutral-to-positive momentum without overbought conditions. The key near-term pivot is 7,680–7,700: holding above this zone supports a retest of 7,750–7,800, while a break below the 20 EMA could expose support near 7,638, followed by 7,516. The base case is range-bound consolidation within a broader uptrend, with a sustained breakout above 7,800 needed to strengthen bullish continuation. This is a technical assessment, not financial advice.


 Nov 02, 2026




 Please wait processing your request...