
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
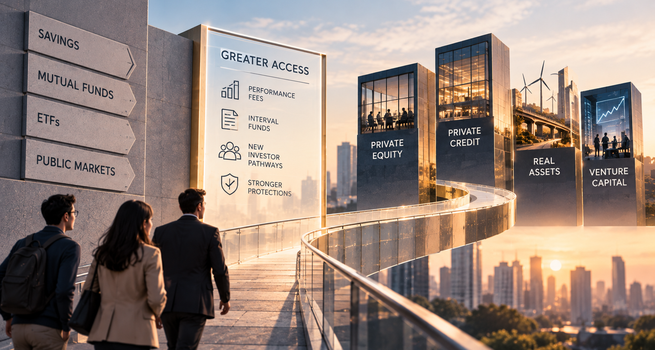
- The SEC voted on 30 September 2026 to propose rules that widen retail access to private market strategies through regulated funds.
- Registered Investment advisers could earn performance-based fees from regulated funds, a feature long associated with Hedge Funds and private equity.
- Interval fund rules would be updated so repurchase schedules better match the Liquidity of underlying assets.
- A separate request for comment explores new routes to Accredited Investor status, including a FINRA exam and professional credentials.
- Redemption pressure at semi-liquid private credit funds earlier in 2026 keeps Liquidity Risk central to the debate.
The US Securities and Exchange Commission has voted to propose amendments that would make it easier for ordinary investors to reach private market strategies. The measures are proposals, so they are not yet in force. They now enter a public comment period of 60 days after publication in the Federal Register, and the final text may differ from what was announced.
The policy direction is clear. Regulators want strategies that were once the preserve of institutions and wealthy households to be available through fund structures that already carry disclosure rules and investor protections. The market backdrop is less settled, because some retail-oriented private credit funds faced heavy Withdrawal requests earlier this year.
Background: Why Private Markets Matter to Individual Investors
Private markets cover investments that do not trade on public exchanges, including private equity, venture capital, private credit and real assets. Companies now stay private for longer, which means a growing share of corporate growth happens before a stock market listing. Investors limited to public markets can therefore miss part of the economy's growth phase.
Access has traditionally been restricted. Private funds usually require investors to meet Wealth or income tests, commit capital for years, and accept limited exit options. The SEC's package tries to loosen these constraints without removing the protections that apply to regulated funds.
What the SEC Has Proposed
The package has four components.
- Performance-based compensation. Registered investment advisers would be able to receive fees calculated on capital gains or capital appreciation from more categories of clients, including regulated funds.
- Disclosure. Fund registration and reporting forms would be amended to require disclosure of performance-based compensation.
- Interval fund modernisation. The framework would be updated, including by allowing repurchases to be scheduled at times that better fit the liquidity profile of the portfolio.
- Multiple share classes. Existing exemptive orders would be replaced with a rules-based framework allowing regulated closed-end funds to issue multiple share classes.
SEC Chairman Paul Atkins has described broader participation in private markets as a priority, and has paired it with a commitment to protect investors from bad actors and fraud.
How Performance Fees Fit In
A performance fee is a share of investment gains paid to the manager, usually on top of a base management fee. It is a defining feature of hedge fund, Private Equity and Venture Capital economics. Because most retail-facing products have been unable to use it, many private market managers have focused on institutional and high-net-worth clients.
Press coverage of the proposal indicates that advisers could charge performance fees of up to 20%, a level comparable to the alternatives industry. If adopted, managers would have a stronger commercial reason to design products for the wealth channel.
The structure has advantages and drawbacks:
- Alignment. Fees tied to gains can reward managers for results.
- Incentive risk. They can also encourage greater risk-taking.
- Valuation sensitivity. For Assets that do not trade daily, reported gains depend on valuation models, which makes valuation governance more consequential.
The proposed disclosure rules are intended to make these arrangements visible in fund filings.
Interval Funds and the Liquidity Design Problem
Liquidity is the hardest issue in retail private markets. Many individual investors are used to mutual funds and exchange-traded funds, where money can usually be withdrawn within days. Private assets such as loans to mid-sized companies or stakes in unlisted businesses cannot be sold that quickly without accepting lower prices.
Interval funds were created to bridge this gap. Instead of daily redemption, they offer to repurchase a set portion of shares at fixed intervals, commonly quarterly. The SEC proposal would let managers schedule these repurchases in a way that better reflects how fast the portfolio can realistically be converted to cash.
A closer match between promised liquidity and asset liquidity reduces the probability of forced selling or sudden restrictions. The outcome will depend on design choices, including how much liquidity is promised, how much of the portfolio sits in more liquid instruments, and how clearly limits are explained to investors.
Accredited Investor Status: Current Rules and Proposed Pathways
An accredited investor is a person the law presumes can evaluate and bear the risks of unregistered offerings. Under current rules, eligibility generally rests on income or net worth thresholds, with limited exceptions for holders of certain securities licences.
The SEC is now seeking comment on adding knowledge-based pathways. It is considering:
- A new accredited investor exam developed by FINRA, testing understanding of securities, investing, and financial and Business matters.
- Recognition of professionals holding the following credentials in good standing: US certified public Accountant licence, Chartered Financial Analyst charter, US Certified Financial Planner certification, and FINRA Series 79, 86 and 87 licences.
This part of the announcement is a request for public comment, not a formal rule proposal. It still signals a possible shift from wealth as the main proxy for sophistication towards demonstrated knowledge.
Market Context: Redemption Pressure in 2026
The proposal follows a period of stress in semi-liquid private credit vehicles. Earlier this year, several funds received a surge of withdrawal requests, including from retail clients, amid concern over software sector debt.
In February, Blue Owl Capital paused regular quarterly cash redemptions in its retail-focused Blue Owl Capital Corporation II fund after requests rose. Blackstone and Apollo were among other managers reported to have received repurchase requests above their funds' quarterly limits.
Industry executives have argued that such limits are a deliberate feature of the structure, protecting remaining investors from fire sales of Illiquid loans. That reading is consistent with how the products are built. It also points to an expectations gap, because a retail investor who sees a quarterly liquidity window may not expect it to be capped or paused when many investors seek to exit together.
Policy Backdrop
The proposals sit within a wider government push. In August 2025, President Donald Trump signed an executive order titled Democratizing Access to Alternative Assets for 401(k) Investors, aimed at allowing more retirement savings to flow into private equity and other alternatives. Atkins has described the SEC's work as complementary, focused on post-tax, pre-retirement savings.
For asset managers, the combined effect is a larger addressable market. For investors and advisers, the practical questions concern fees, valuation and exit terms.
Key Factors in Evaluating Retail Private Market Funds
Several analytical issues will shape how these products are assessed if the rules take effect:
- Valuation method. Private assets are valued through models and periodic appraisals, so reported returns can appear smoother than underlying economic volatility.
- Fee layering. Products may carry management fees, performance fees and fund-level expenses. Comparing net returns requires clear, standardised disclosure.
- Liquidity terms. Repurchase limits, notice periods and gating rights determine how and when money can be withdrawn.
- Concentration and credit quality. Diversification within a fund does not remove exposure to a shared sector or economic shock, as early 2026 showed.
- Distribution readiness. Wealth platforms and advisers need systems to explain lock-ups and repurchase limits accurately.
Arguments For and Against
Supporters argue that individual investors have been shut out of a growing share of corporate returns, and that regulated structures offer more transparency than unregulated alternatives. Sceptics worry that complex, illiquid products could reach people who do not fully understand them, and that higher fees could erode net returns.
Both positions have analytical merit, and the final rules will likely reflect a negotiation between them. The probability of meaningful amendments before adoption is material, given the breadth of the package and the range of Stakeholders likely to comment.
Timeline and What to Watch
- The comment period runs for 60 days after Federal Register publication.
- Feedback from asset managers, investor advocates and industry groups will indicate which provisions face resistance.
- Changes to fee limits or disclosure standards in the final text would affect product economics.
- Redemption trends across semi-liquid funds in coming quarters will inform how regulators and the market judge liquidity design.
Outlook: Wider Access, Unresolved Liquidity Questions
The SEC package addresses incentives through performance fees, structure through interval funds and share classes, and eligibility through accredited investor reform. If adopted, it would mark one of the most significant steps in recent years towards bringing private markets closer to individual savers.
The central challenge remains unchanged. Private assets move slowly, while retail investors expect flexibility. How well the final rules align fund design, disclosure and investor expectations will largely determine whether wider access strengthens capital formation or exposes new weaknesses.

 Oct 28, 2026
 Please wait processing your request...