
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Anthropic's amended S-1 filed on November 2, 2026 shows third-quarter Revenue of USD 17.0 billion and nine-month revenue of USD 33.2 billion for the period to September 30, 2026.
- The operating loss was USD 567 million in the third quarter and USD 1.26 billion for nine months, about 3.8% of nine-month revenue, simple arithmetic on two filed numbers.
- The nine-month net loss was USD 104.0 billion, mostly a USD 94.3 billion non-cash charge tied to convertible notes and similar instruments, per published coverage of the filing.
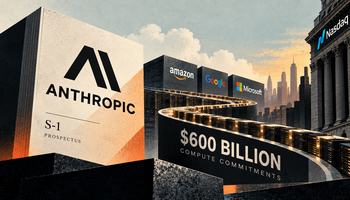
- Signed contracts total about USD 895.4 billion, mostly for computing and infrastructure, with about USD 69.8 billion due in the 12 months after September 30, 2026.
What the Filing Shows
Anthropic is a private company, and the amended registration statement filed on November 2, 2026 adds third-quarter figures to its earlier S-1. Revenue of USD 17.0 billion in the quarter compares with USD 33.2 billion for nine months, which implies about USD 16.2 billion across the first half. The operating loss was small against that revenue, but the net loss was large because of a non-cash charge of USD 94.3 billion on convertible notes and similar deals. Such charges can arise when the value of a conversion feature changes with the company's valuation. The filing leaves the share count, price range and offering amount blank. The filing also confirms that Class A shares would be offered to the public.
The Commitments and the Control Structure
The commitments figure is the one most investors will study. Contracts of about USD 895.4 billion are mostly for computing and infrastructure, of which about USD 213.8 billion can be cancelled or depends on conditions and about USD 451.2 billion covers leases signed but not yet started. Named suppliers with disclosed amounts total USD 643.8 billion. On governance, public investors would hold Class A shares with one vote each, a Long-Term Benefit Trust holds a Class T share that elects a majority of the board, and seven co-founders hold a Class F share with 50.1% of the vote for the remaining board seats. About USD 69.8 billion of the commitments fall due within 12 months after September 30, 2026, which is the portion with the nearest cash impact.
Risks and What Is Still Unknown
The filing lists risks including falling behind rivals on models, securing enough computing, dependence on co-founders and key researchers, misuse of its models, customer concentration, a government dispute involving a supply-chain risk label and Data Center moratoriums in some locations. Published coverage says the company may soon meet a Responsible Scaling Policy threshold but has not designated any current model as exceeding it. There is no IPO date or price, and coverage points to a Nasdaq listing, but no valuation can be derived from the filing alone. Anthropic's figures are company-reported and unaudited for the quarter in published summaries.
Where Things Stand
The filing shows a Business growing fast, with USD 17.0 billion of third-quarter revenue and a nine-month operating loss near 3.8% of revenue, but it also shows USD 895.4 billion of commitments that must be financed. A quarterly revenue number of this size answers the question of scale, not the question of durability. A large share of the commitments is conditional or not yet started. No price, date or share count has been set, so any valuation view is premature. Published coverage notes November 10, 2026 as the earliest road show date under SEC staff practice, which is not a forecast.

 Oct 28, 2026
 Please wait processing your request...